In this guide, we’ll focus on the 183-day rule and the questions expats ask most. Crossing into Spanish tax residency can shift you from paying tax only on Spanish-source income to reporting worldwide income under IRPF, Spain’s personal income tax.
Key takeaways
- Spain usually treats you as tax resident if you spend more than 183 days there during the calendar year.
- The days do not need to be consecutive in most cases, so separate stays can still add up.
- Spain can still treat you as a resident under 183 days, if your center of economic interests or your family ties point there.
- Tax residency is not the same as visa status or the Schengen 90/180 rule.
- Once residency applies, Spain may tax worldwide income, so it’s worth checking current AEAT guidance or speaking to a Spain-qualified adviser.
This guide is for general information only, not tax, legal, or financial advice. For the broader framework, check out our guide to tax residency in Spain.
What makes you a tax resident in Spain?
Spain can treat you as resident through more than one route. As Barcelona-based advisory firm Centre Gestor says, “Becoming a tax resident in Spain is not just about how long you stay, but about where your life is centered.”
The three tests Spain uses
The Agencia Tributaria, or AEAT, Spain’s tax agency, looks at three main domestic tests. The 183-day rule is the best known one, but remote workers, retirees, business owners, and families also need to look at the other two.
| Test | What it means | What it can look like in practice |
|---|---|---|
| More than 183 days in Spain | You are in Spain for more than 183 days during the calendar year | A retiree or remote worker spreads long stays across the year and goes over the limit |
| Center of economic interests | Spain is the main base of your professional activity or economic interests | A consultant lives abroad on paper but manages clients, income, or a business mainly from Spain |
| Spouse and dependent children in Spain | Spain may presume residence if your non-separated spouse and dependent minor children habitually live there | A parent travels for work but the family home and daily life are clearly in Spain |
Why the calendar year matters
Spain usually treats you as resident or non-resident for the entire calendar year. In practice, Spanish domestic law does not create a simple part-year resident status just because you arrived in July or left in October.
That is why mid-year moves can create false confidence. Treaty analysis with another country may still matter in edge cases, but the domestic starting point is the full calendar year.
Wise account
Are you an expat or thinking of moving to Spain? Managing your money across borders shouldn’t be complicated. With a Wise account, you can hold over 40 currencies and pay with a Wise debit card in more than 150 countries. Whether you need to spend abroad, receive or send money home, Wise can help make international money management simpler.

How Spain counts the 183 days in practice
Counting days gets tricky once you mix short stays, weekends away, and travel days. The safest approach is to track presence carefully instead of relying on rough memory.
Do arrival and departure days count?
Spanish law does not frame the test around overnight stays. In practice, Spain-based advisers usually tell expats to count any day of physical presence in Spain, including arrival and departure days, rather than assuming only full days count.
A simple example shows why this matters:
- January through March in Barcelona, 82 days
- May through July in Valencia, 78 days
- September through October in Málaga, 30 days
That makes 190 days, even though none of the stays was in one continuous block.
How sporadic absences and proof work affect tax residency
AEAT says sporadic absences can still be counted unless you prove tax residence in another country. When your total is close to the limit, the argument often turns on documents rather than recollection.
Useful proof can include travel logs, leases, utility bills, employer letters, school records, and a certificado de residencia fiscal, or tax residency certificate, from another country where relevant.
When you can be resident even under 183 days
Staying under 183 days does not automatically keep you outside Spanish tax residency. Spain can still look at where your work, money, and family life are genuinely based.
Center of economic interests
The center of economic interests test asks whether Spain is the main base of your professional activity or economic interests, directly or indirectly. For a remote worker, that may mean Spanish clients or a daily work pattern centered in Spain. For a business owner, it may mean the place where management decisions are really being made.
One risk here is assuming one foreign employer settles the issue. What matters is the wider fact pattern, not just the name on one contract.
Family ties and the presumption rule
Spanish rules also create a presumption of tax residence when your non-separated spouse and dependent minor children habitually live in Spain, unless you can prove otherwise. This matters for internationally mobile families because the family home can point one way even when one parent travels often.
For example: a parent works across several countries while their spouse and school-age children are settled in Madrid. Even below 183 days, that fact pattern may still raise a Spanish residency question.
What changes once you become a Spanish tax resident?
Once the answer starts to look like yes, the next issue is scope. The practical difference is what income Spain expects you to report.
Worldwide income, IRPF, and common forms
Spanish tax residents typically fall under IRPF, or Impuesto sobre la Renta de las Personas Físicas, while non-residents usually fall under IRNR, or Impuesto sobre la Renta de no Residentes, on Spanish-source income only.
| Status | Tax scope | Common forms |
|---|---|---|
| Resident | Usually worldwide income, such as salary, pensions, rent, and investments | Often Modelo 100 through the income tax filing process in Spain |
| Non-resident | Usually Spanish-source income only | Often Modelo 210 and related non-resident filings |
| Special impatriate regime | Special treatment for some eligible newcomers | Often Modelos 149 and 151 |
For salary, pensions, rent, and investments abroad, this is the point where tax residency in Spain starts to matter in practice. Spanish tax residency depends on your individual facts and, in some cases, tax treaty analysis with another country.
Regional taxes, wealth tax, and foreign asset reporting
Spain is not fully one-size-fits-all. Your comunidad autónoma, or autonomous community, can affect the final outcome for some taxes, and higher net worth readers may also need to review wealth tax or foreign-asset reporting.
Madrid, Catalonia, and Andalusia are often used as examples because regional treatment can differ. Navarra and the Basque Country follow separate systems, so national summaries may not tell the full story there.
Tax residency is not the same as legal residency or Schengen time limits
Many expats mix these rules together, but they answer different questions. A visa or residence permit tells you whether you can live in Spain under immigration rules, while tax residency helps decide where income may be taxed.
- Tax residency: Decides whether Spain may tax worldwide income or only Spanish-source income.
- Legal residency: Covers your immigration status, such as work, family, or digital nomad visa status in Spain.
- Schengen 90/180 rule: Limits short stays for many non-EU visitors in the Schengen Area.
You can hold a residence permit and still be non-resident for tax purposes, or become tax resident without the immigration outcome you expected. Mixing up tax rules with border-stay rules is a common mistake which can lead to bad filing decisions.

How to check your status and keep records
Treat the legal tests as an admin routine before filing season. If your movements or income cross borders, a basic paper trail can save stress later.
Documents that help prove residency or non-residency
Keep records that show where you were, where you lived, and where your real work or family life sat during the year. That can include travel logs, tickets, leases, utility bills, padrón, or town hall registration, employer letters, school records, and a tax residency certificate from another country.
If you are still setting yourself up, make sure your ID numbers in Spain and tax records line up with the rest of your paperwork.

Expatica Content Editor
Connor Glaze
Insider Tip
Schengen travel often leaves no passport stamp, so keep flight confirmations, train bookings, and card statements because AEAT may care more about your paper trail than your memory.
Compliance checklist:
- Count all days in Spain across the full calendar year.
- Check whether your work, business, or income base points to Spain anyway.
- Review whether spouse and dependent children habitually live in Spain.
- If another country may also treat you as resident, gather treaty and certificate evidence early.
When to get professional help
Professional support is worth considering if you could be resident in two countries, have mixed income sources, own a company, hold large assets, or need treaty analysis. It may also be useful if you’re simply feeling overwhelmed by your own research and need confirmation on any confusing details. A practical next step is to review current AEAT guidance first, then use Expatica’s accountants and tax preparation directory if your facts span more than one country.
Can the Beckham Law or a tax treaty change the outcome?
Special regimes and treaties can change the final tax treatment, but they apply only after residency is established. They do not replace that first determination.
When the Beckham Law may be relevant
Some qualifying inbound workers, teleworkers, and other eligible newcomers may be able to use Spain’s special impatriate regime, often called the Beckham Law in Spain. Do not assume it applies automatically just because you moved for work.
Deadlines and conditions matter, and the regime can change what income the Spanish government taxes and how it is reported. If it looks relevant, check the official AEAT guidance and the Expatica explainer before you act.
How treaty tie-breaker rules work
If both Spain and another country claim you as resident under their own domestic rules, a double tax treaty may help break the tie. The usual order is permanent home, center of vital interests, habitual abode, and nationality, with the authorities resolving the case if those tests still do not settle it.
Example: Someone keeps a home in the United States, moves to Spain in spring, and works partly in both places. A treaty can reduce conflict, but it still depends on the real facts.
Managing money across borders while living in Spain
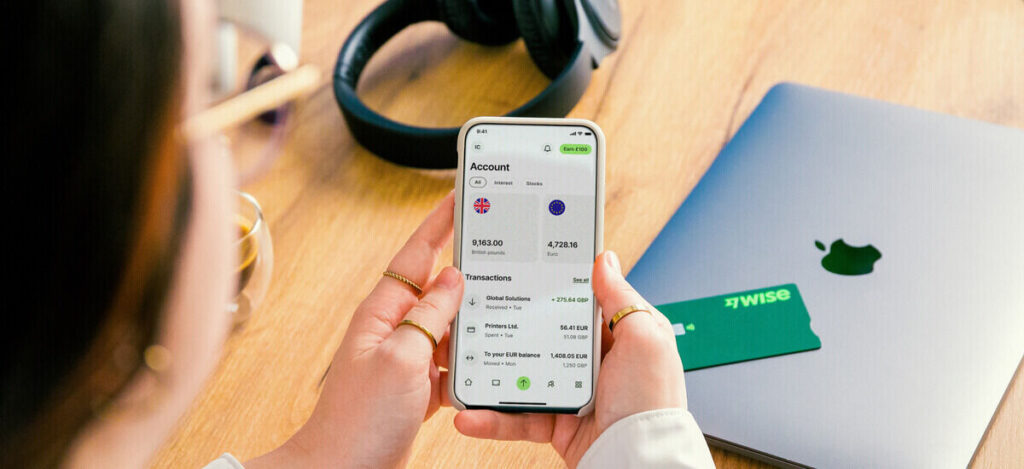
Tax residency questions often sit next to everyday money admin. You may need to convert savings into EUR, pay Spanish taxes or bills, and still spend in more than one country.
Major local banks such as Santander, BBVA, and CaixaBank can make sense for local direct debits and branch access. If you still move money between currencies, it is also worth planning how you will hold funds, make transfers, and pay abroad without added friction.
One practical option is the Wise account for expats who need to hold money in different currencies, transfer money between them, and spend with a card in multiple countries. It does not solve tax questions, but it can simplify everyday cross-border payments.
FAQ
FAQ
Do the 183 days in Spain have to be consecutive? 
No, not usually. Spain normally looks at the total days you spend in the country during the calendar year, so several shorter stays can still take you over the limit.
Can Spain treat me as a tax resident if I spend fewer than 183 days there?
Yes, it can. Spain may also look at your center of economic interests and, in some cases, where your spouse and dependent minor children habitually live.
How do I prove I am not a Spanish tax resident?
You may need a tax residency certificate from another country plus supporting records such as travel evidence, housing documents, and work or family records. Visa status on its own is not enough proof for tax purposes.
Is Spanish tax residency the same as the Schengen 90/180 rule?
No. The Schengen rule is a border-stay rule for many short-term visitors, while tax residency is about where income may be taxed.
Sources
Expatica’s experts are all about providing the most up to date and accurate information. All guides are fact checked, and whenever we use external sources (like government websites or research papers) we’ll make a note of them here so you can check them out too.
- Individual resident in Spain, Tax Agency
- Tax residency certificates, Tax Agency
- Personal Income Tax, Tax Agency
- Non-residents, Tax Agency
- Double taxation agreements signed by Spain, Tax Agency
- Special regime for inpatriates art. 93 Personal Income Tax Law, Tax Agency
- How to know if you are a Tax Resident in Spain, Centre Gestor
- Tax resident in Spain: How to calculate the 183 days?, AGM