


Finance
Insurance
Car insurance in Spain

Getting car insurance is an essential part of driving legally in Spain. Whether you’re bringing your own vehicle or buying one locally, understanding the Spanish insurance system is crucial for expatriates. This guide covers everything you need to know about car insurance in Spain, including types of coverage, costs, and application processes. As you prepare for your move, remember that managing finances across borders can be challenging – services like Wise can help you transfer money to Spain with the mid-market exchange rate, making it easier to set up your new life including paying for essentials like car insurance.
To help you understand the Spanish car insurance market, this guide examines the key issues, including:
An overview of car insurance in Spain
You need to insure all vehicles in Spain to at least third-party liability level. This includes cars, trucks, RVs, motorbikes, and scooters. However, bicycles don’t require insurance. Anyone caught driving without insurance by Spanish police can be fined up to €3,000.
To get car insurance in Spain, you will need to register the vehicle. You can drive foreign vehicles for a limited period (3-6 months) without Spanish registration but will need to have at least third-party insurance. All vehicles need insurance, even those that are parked or inactive, although insurers will usually only cover roadworthy vehicles.
As in many countries, insurance is applied to the vehicle rather than the driver. You can add drivers to the policy, although those aged under 25 or with a poor driving record may affect premiums. Policies can often be transferred to another vehicle in the event of a sale, although premiums may change.
Car insurance is one of the biggest Spanish insurance markets, accounting for 31.5% of non-life insurance in 2017. The Directorate-General for Insurance and Pension Funds (Direccion General de Seguros y Fondos de Pensiones – DGSFP) regulates insurance companies in Spain.
See more information in these guides on insurance in Spain, driving in Spain, and Spanish driving licenses.
Feather car insurance
Feather offers car insurance in Spain designed for expats, with a fully digital sign-up process and English-speaking support from quote to claims. Policies can recognize a clean driving history from abroad, potentially reducing costs, and include practical extras such as legal support for traffic fines, license-point recovery costs, and cover for additional occasional drivers.

Motorcycle insurance
Anyone who rides a motorcycle, moped, or scooter in Spain requires third-party liability insurance as a minimum. You can also take out extended policies that cover you for theft, roadside assistance, and more, depending on the classification of your vehicle. To purchase coverage, you need a driving license that is valid in Spain. Motorcycle insurance providers in Spain include Linea Directa.
Can you use car insurance from another country in Spain?
If you move to Spain from another EU country, you can continue to use your existing insurance policy. However, you will need to check with your insurer that you have international coverage.
Citizens from non-EU countries may be able to use insurance from their home country for a limited period (3-6 months), but if you are relocating to Spain from a non-EU nation then you will need to register your car and buy car insurance in Spain once this period ends.
If you’re temporarily visiting Spain with a car registered abroad, your home insurance policy may cover you through the Green Card system. However, if you’re becoming a resident, you’ll need to register your vehicle in Spain and obtain Spanish insurance.
When managing insurance policies across different countries, be mindful of currency conversion costs. Banks often add hidden markups to exchange rates when transferring money internationally. Using Wise can help you avoid these hidden fees by offering the mid-market exchange rate when transferring money to pay for your Spanish insurance premiums.
Types of car insurance in Spain
The three main types of car insurance in Spain are:
Third-party liability (responsabilidad civil obligatoria or seguro obligatorio)
This typically covers all damage and costs incurred by third parties including vehicle damage, personal injuries, and legal costs. However, a standard policy won’t cover any of your own costs.
You can tailor third-party insurance to include extras such as roadside assistance, so be mindful of coverage and exclusions when purchasing this type of insurance. It’s a worthwhile option if you have an older or inexpensive car, or if you don’t drive often.
Third-party fire and theft (responsabilidad civil obligatoria, incendio y robo)
This covers standard third-party claims plus will also cover a certain amount of damage to your own vehicle. This typically includes fire damage, storm damage, natural disasters, and accidents, plus theft and vandalism.
As with standard third-party liability policies, you can tailor this insurance to meet your requirements.
Comprehensive (todo riesgo)
This type of insurance covers all costs incurred by both yourself and third parties, even if the accident was your fault. Be mindful, though, that companies usually won’t pay out if you are in violation of the law (e.g., driving while drunk).
Comprehensive insurance is sensible if you have an expensive car that will cost a lot to repair, if you drive every day or if there are particular risks associated with your driving. However, don’t forget that your premiums will rise in line with increased risks.
Car insurance costs
Car insurance premiums in Spain averaged at just over €350 per year in 2016, just above the EU average. Premiums have come down from an average of over €450 in 2005. Third-party coverage can be as cheap as €150 but will usually be around €250–300. Fully comprehensive policies are likely to be €400 a year or more.
As with most countries, Spanish premiums are determined by factors including vehicle value and age, driver profile and age, and any additional risks associated with the policy. In Spain, your place of residence is also important, with higher premiums associated with busier cities such as Madrid and Barcelona.
You can reduce your annual premiums by voluntarily increasing your excess or deductible, which is the amount you have to pay toward each claim. Most policies have a compulsory excess amount, although comprehensive packages can usually be taken out without any excess. These will be more expensive than standard comprehensive policies. Some insurers also offer temporary (3–6 months) policies at a higher monthly rate.
Additional forms of car insurance in Spain
Aside from standard third-party and comprehensive policies, most companies also offer additional coverage. Here are some of the most common types:
- Breakdown assistance – covers towing and repair costs, along with replacement transport costs;
- No-claims protection – allow you to protect your no-claims bonus if you make a claim;
- Legal expenses insurance – covers legal fees in the event of a court case arising from an accident;
- Personal accident insurance – covers medical costs and can provide compensation in the event of death or disability.
Car insurance bonuses and penalties in Spain
Spain operates a no-claims bonus system where drivers can reduce their premiums year-on-year if they don’t file any claims. Each company will have its own no-claims schedule. Typically, you will earn a 5% discount for each no-claim year. The maximum discount is around 65%.
You can carry over no-claims periods from other insurers when switching providers if you are able to provide proof of no-claims history. Spanish insurers usually recognize no-claims periods earned in other EU countries. They may also acknowledge good driving records from certain non-EU countries, but this varies from insurer to insurer.
While no-claims periods earn discounts, premiums are likely to increase if you have a history of accidents. Expect to pay through the nose if you:
- have been involved in any incidents that were your fault;
- have any points on your license for things such as speeding or drink-driving;
- are a young or inexperienced driver. Drivers aged under 25 in Spain usually have to pay higher premiums.
Car insurance companies in Spain
Providers of Spanish car insurance include:
- AXA
- Catalana Occidente
- Linea Directa
- Mapfre Seguros
If you’re finding it difficult to choose between insurance companies, Acierto.com can help you compare their services. In addition, you can explore our Spanish Business Directory to find other insurers.
How to choose Spanish car insurance
It’s a good idea to shop around when looking for car insurance in Spain, taking into consideration a wide range of factors rather than just automatically choosing the cheapest policy. Other factors you might want to consider are:
- No-claims bonus – what discounts does the company offer and can you transfer no-claims periods from abroad?;
- Policy coverage – third party and comprehensive coverage can vary from company to company. What is included and how much does it cost to add on what you might need?;
- Excess/deductible options – is there a mandatory excess and what are the options for increasing it voluntarily?;
- Company reputation – what are customers and reviewers saying about this company and its practices?;
- Claims process – how straightforward is it and how quickly will you get reimbursed when making a claim?;
- Roadside assistance – what level of coverage does the company offer and will this cost extra?
Applying for car insurance in Spain
Each car insurance company will have its own application process. In order to simplify the process, most companies now allow customers to apply online. A few smaller companies may ask you to apply over the phone or by email.
Most insurers will ask for the following as a minimum requirement:
- Spanish driving license or license that can be used in Spain
- NIE number
- Spanish address of policyholder
- Spanish bank account details
Once the insurance company processes your application, you should receive your insurance certificate, EU accident statement form, and green card for use if you use your Spanish car insurance overseas. It is no longer a legal requirement to carry your car insurance documents in your vehicle, although it’s worth having a copy to hand just in case you need to show proof of insurance at any time.
Making a claim with a Spanish car insurer
Companies will have their own claims process which they should clearly explain to you when you take out an insurance policy. In general, you will be expected to do the following as a part of making any claim:
- complete your EU accident report form (declaración de siniestro de automóvil) which should be signed by both parties;
- obtain a copy of the police report form, if you are involved in an incident where the police are called;
- get the contact details of the other party along with any witnesses to the accident;
- take pictures of the damage if possible.
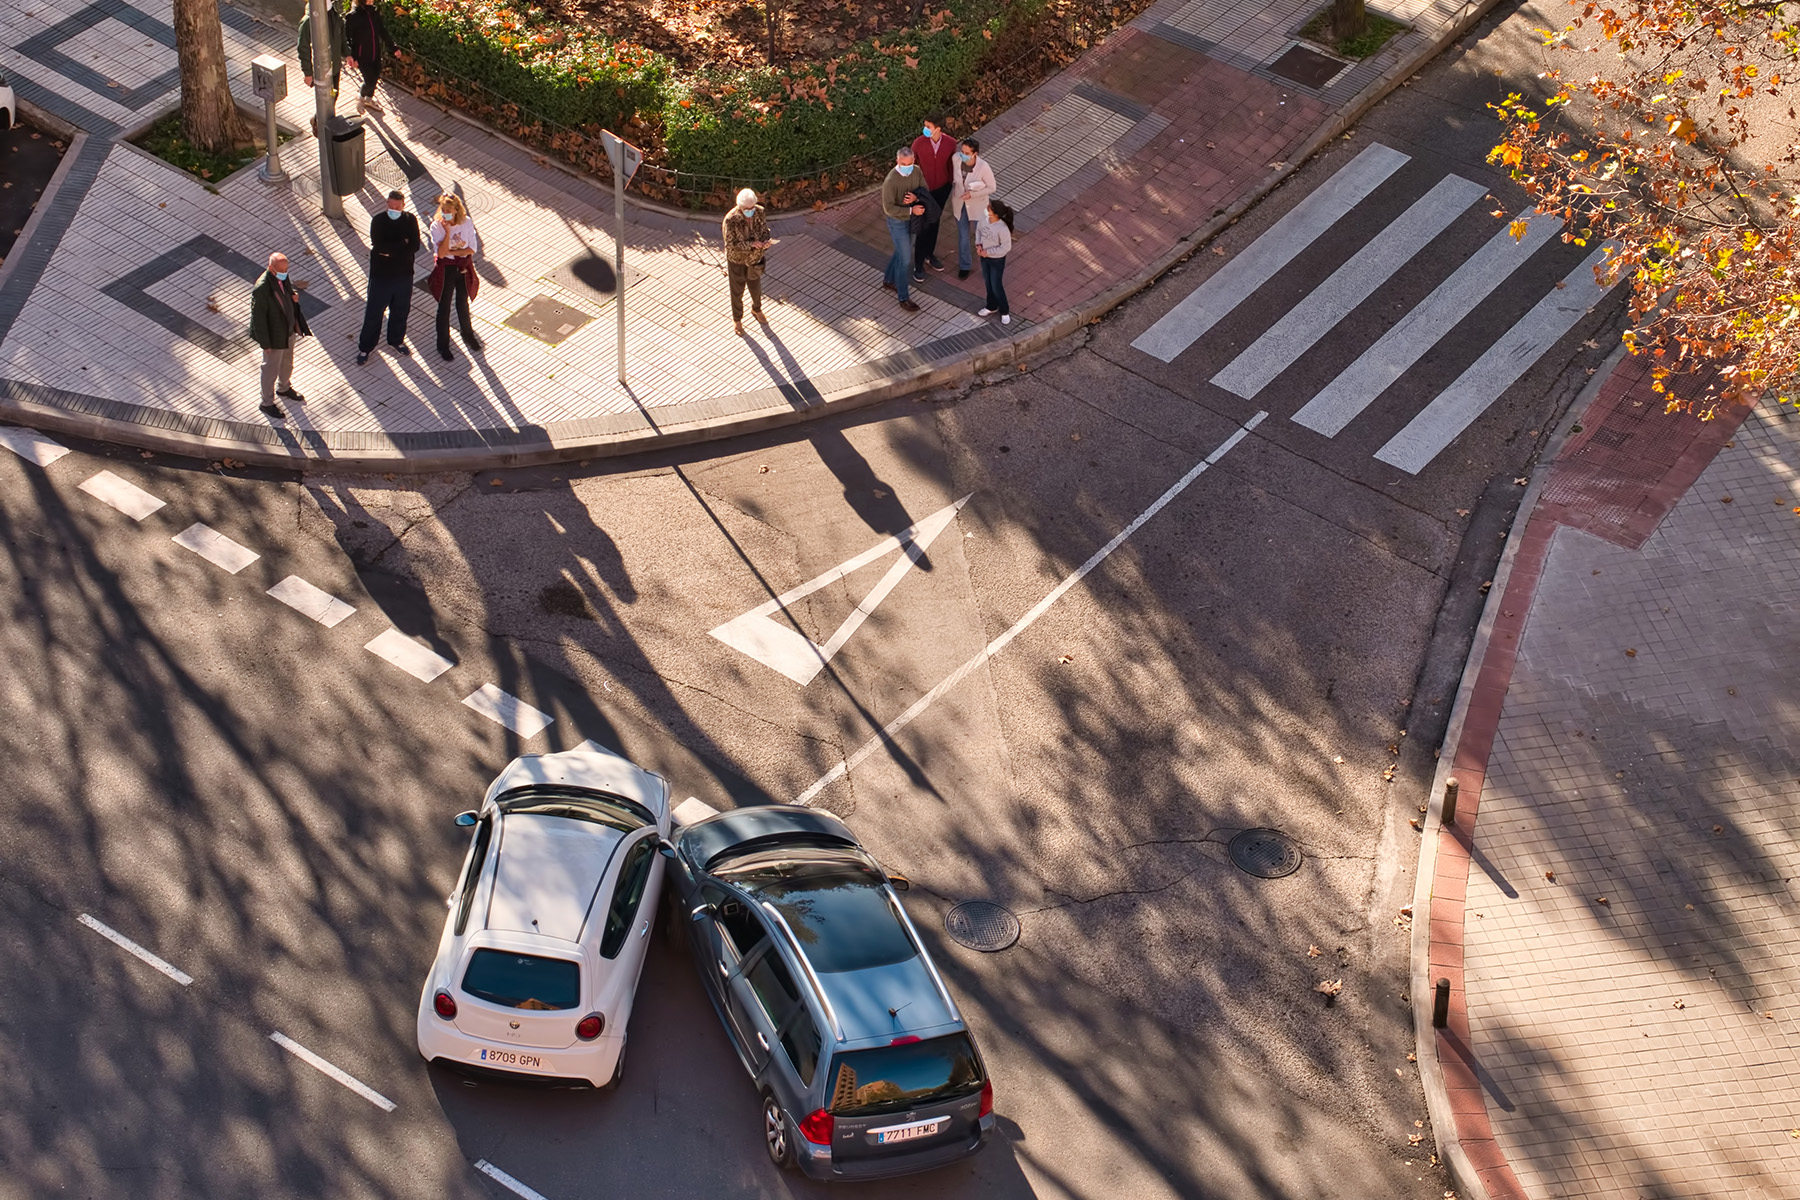
If you have comprehensive insurance and are making a claim for damage to your own car, your insurance company will usually assess the damage before paying out for repairs. Spanish companies normally only pay out a percentage of the vehicle value if it is written off.
You will usually have a set time period in which you have to file a claim. This is normally within 2-5 days of the accident. Thefts should be reported both to the police and your insurer immediately. Insurance companies will wait 30 days before paying out in the event of car theft.
Canceling a contract or changing provider
Car insurance policies in Spain automatically renew after the contract period ends. Therefore, you will need to inform your provider if you wish to cancel or switch to another company.
Companies all have their own cancellation policies, terms, and conditions. You can usually cancel mid-contract with two months’ notice, however, you probably won’t be refunded for any amounts paid upfront. As Spanish premiums are usually payable in six-month or yearly amounts, be careful that you don’t lose out.
You can usually cancel without penalties for the following reasons:
- your insurer increases your premiums or alters the terms of your contract;
- the insured vehicle is written off or stolen
Your insurance company is legally entitled to refuse to renew the contract if they give you 15 days’ notice when it’s due to end.
Typically, you will have to write a letter or email to your insurance company informing them of your intention to cancel along with reasons for doing so. Some companies now allow customers to cancel online.
Making a complaint about a Spanish car insurance company
If you want to complain about a Spanish car insurance company, you should follow these steps:
- Step one – file a complaint in writing with the Ombudsman or Customer Service Department of your insurance company. Your insurer should provide you with details of its Ombudsman. If not, you can find them through the DGSFP website.
- Step two – if you’re not happy with the response or you don’t receive a response within two months, you can take the complaint to the DGSFP. They will assess the complaint after contacting the insurer and issue a report stating whether they feel the company has complied with the law;
- Step three – if you are still not happy, you can go to court. You are also entitled to go to court prior to filing a complaint with the DGSFP. However, bear in mind that you will be responsible for court costs.
Roadside assistance in Spain
Many insurance companies in Spain offer breakdown assistance as an optional extra. Some comprehensive policies all include this as a standard.
You can also choose to join a membership club such as the Spanish Royal Automobile Club (RACE). Overseas organizations such as the RAC also provide breakdown cover in Spain.
If you break down on the Spanish roads, you should try and move your vehicle to the nearest safe place (e.g. a road lay-by) and contact your coverage provider. If you don’t have coverage, RACE can help you but you’ll have to pay for the service.
Breakdown assistance usually covers the cost of towing, alternative transportation for the car driver and passengers, and emergency repair costs. RACE membership costs around €16.50 per month which includes roadside cover in other countries.
Useful resources
- Directorate-General for Insurance and Pension Funds (Direccion General de Seguros y Fondos de Pensiones – DGSFP) – insurance regulator in Spain
- Spanish Royal Automobile Club (RACE) – membership automobile association that provides breakdown assistance among other services
Related Articles


Editor's picks
 Guide to getting health insurance in Spain in 2026Find out whether you need private health insurance in Spain in 2026, with insider info on costs, coverage, and medical professionals.
 Top 10 Spanish foods – with recipesWhat better way to explore Spain than with your tastebuds? From tasty tapas to delicious dishes, here are the best Spanish foods.
 International schools in SpainWant to send your child(ren) to an international school in Spain? Find out everything you need to know about fees, exams, and more.
Did you find this guide helpful?