


Healthcare
Healthcare Basics
Guide to getting health insurance in Germany in 2026
Explore the best expat health insurance options for Germany in 2026, including eligibility for public insurance (GKV) and private coverage (PKV).
Everyone living and working in Germany must have health insurance, and it’s essential to have the right coverage so you can avoid pricey medical bills. The country’s healthcare system ranks among the world’s best, but navigating the public and private insurance options as an international requires research and patience.
Whether you’re eligible for public health insurance (gesetzliche Krankenversicherung – GKV) or need private insurance (private Krankenversicherung – PKV), this article explains the key differences, how to get coverage, and the requirements based on your circumstances.
Sections include:
Feather
Feather is a digital-first insurance provider built for expats that combines a fast online signup with real human support. Their insurance plans are easy to understand, fully in English, and can be purchased within minutes. Customers get instant access to visa-ready documents, clear guidance throughout the process, and an English-speaking support team available whenever they need help.

Health insurance in the German healthcare system
Germany has a universal healthcare system, meaning everyone living in the country has access to necessary care.
Healthcare in Germany is funded by two separate systems:
- Public health insurance (gezetzliche Krankenversicherung): this is often known as ‘statutory health insurance’ or by its German initialism – GKV.
- Private health insurance (private Krankenversicherung): referred to as PKV.
All German residents must have medical insurance, and statutory health insurance (GKV) is mandatory for most. In fact, private insurance is only available to those who meet specific criteria, such as high earners, the self-employed, civil servants, and students over 30.
The Federal Joint Committee (Gemeinsamer Bundesausschuss – G-BA) decides what GKV covers and determines standards for medical care.
Public and private health insurance in Germany
Although the German healthcare system is predominantly covered by the state, residents may purchase supplemental healthcare coverage (Krankenzusatzversicherung) from a private provider.
This can be useful for situations where you might need to pay for additional services in a hospital or for healthcare not covered by GKV, such as some types of dental work, optical care, or alternative medicine.
Some people can choose to go fully private. These include high earners, civil servants, self-employed people, and certain students.
Who needs health insurance in Germany?
Health insurance is mandatory in Germany. That means that everyone living in the country must have at least basic public or private coverage.
So, if you’re a foreigner coming to Germany, the following applies:
- EU/EEA citizens can use their European Health Insurance Card (EHIC) when staying for up to 90 days, after which they must apply for GKV or PKV. The same applies to those carrying a United Kingdom Global Health Insurance Card (GHIC).
- Non-EU/EEA citizens must provide proof of suitable health insurance when applying for a visa or residence permit. You may need a policy for the first three to six months of living in Germany.
If you are moving to Germany from another EU/EEA country where you receive a pension or social security benefits, you can use the S1 form to transfer your healthcare rights. You can request this form from your health insurance authority in the country where you live. It ensures you will continue to receive benefits in Germany under the public system.
What happens if I don’t have health insurance?
If you do not have health insurance coverage, you will not be prosecuted, but you may face hefty bills and only receive emergency treatment. In other cases, doctors may refuse to see you.
It’s also essential to organize your health insurance as early as possible when moving to Germany, otherwise you may need to pay outstanding contributions and late payment surcharges after treatment.
Who can access GKV in Germany?
Before we dive into the details below, here’s a quick overview of who needs what type of health insurance:
| What is your status? | Can you access statutory health insurance (GKV) in Germany? | When do you need private insurance? |
| Employee of a German company | Yes. If you earn under €77,400 per year, GKV is mandatory. | To top up your statutory coverage If you earn over €77,400 per year |
| Employee of a foreign company | Yes, if you are resident in Germany. GKV may be mandatory – check with your employer. | To top up your statutory coverage If you earn over €77,400 per year When seconded, staying temporarily, or if your company is not registered in Germany (check with your employer) |
| Job seeker | EU/EEA/Swiss citizens receiving unemployment benefits can transfer their healthcare rights to Germany. Without benefits, you must contact your health insurance company and check if your current rights grant you an EHIC. Unemployed citizens from other countries can only register for public health insurance in Germany if they have already worked in the country. | If you are a citizen from a non-EU/EEA country If you are an EU/EEA/Swiss citizen, it depends on your existing coverage. |
| Student | Yes, if you are under 30. Over-30s can, but on a different scheme. You can use your EHIC if you are from a EU/EEA country, and your GHIC if you are from the UK. If you don’t have an EHIC, you can use the S1 form to transfer your existing medical benefits. | Private coverage can be cheaper than statutory health insurance if you are a student over 30. To top up existing coverage |
| Retiree | Yes, if you are a citizen of a EU/EEA country, by filling out the S1 form and getting your healthcare rights transferred. Non-EU citizens can only access GKV if they have previously contributed to the system. | If insured privately in your home country (EU/EEA) Non-EU citizens usually need private insurance if moving to Germany as a retiree. |
German statutory health insurance (GKV)
Statutory health insurance is part of the Germany’s social security system. GKV ensures that all residents with mandatory insurance can access necessary medical services. This coverage is available to everyone eligible, regardless of pre-existing conditions, and contributions are based on income level.
Although public health insurance is funded by the state, you must still sign up with a health insurance fund (Krankenkasse). Employees are usually automatically signed up with their employer’s chosen fund, but you can choose another if you’d prefer.
When you have statutory health insurance, you are automatically enrolled in long-term care insurance in Germany (Pflegeversicherung). This coverage helps cover the costs of nursing care and other support services that may be necessary due to aging, medical conditions, or disabilities.
Who can register for German public health insurance?
Around 90% of the German population is registered with statutory health insurance (GKV). You must be a legal resident of Germany and register with the local residents’ office before you can apply.
GKV takes effect immediately and can be used retroactively. Family members are also covered when you register, as long as they are:
- Resident in Germany
- Not already insured
- Not exempt from insurance
- Not self-employed full-time
- Do not have a regular income of over €538 per month (2026)
State health insurance for employees
If you work for a German company and earn under €77,400 per year, you are likely eligible for GKV. Contributions form 14.6% of your salary – your employer pays half, while the other half usually comes directly out of your wages.
Employees of foreign companies must also make sure they are registered for health insurance – check with your employer to find out whether you are eligible for GKV. Usually, you register with social security and make contributions, and your employer reimburses you for half of the costs.
Medical insurance for freelancers and entrepreneurs
Self-employed persons and freelancers (Freiberufler) must have health insurance. However, unlike employees, you can choose whether to take out statutory or private health insurance.
Most freelancers must make 100% contributions to health insurance, whether GKV or PKV. Considering that GKV constitutes 14.6% of your income, while PKV is a set price, you may find that going private works out cheaper, depending on your age, income, and pre-existing conditions.
However, an exception to the 100% rate applies to self-employed people in artistic and journalistic professions. If eligible, you can join the Artists’ Social Insurance Fund (Künstlersozialkasse – KSK). This fund organizes contributions so that freelance artistic professionals only pay 50% of their health insurance costs. The state and companies that use artistic services cover the remaining half.
Can you access statutory health insurance in Germany if you are unemployed?
Jobseekers and unemployed people must also have health insurance. You are entitled to state health insurance if you have already worked in Germany and have been making contributions to social security.
Usually, if you have been working in Germany and lose your job, your health insurance will automatically continue, but you must inform your provider of your unemployment. If you are receiving unemployment benefits, the Federal Employment Agency or Job center will cover the contributions. Depending on the benefit you receive, privately insured jobseekers may need to switch to statutory insurance while unemployed.
Meanwhile, if you move to Germany as a jobseeker, the following applies:
- Previously publicly insured EU/EEA citizens may be able to use their EHIC/GHIC for emergency treatment for the first 90 days. If you intend to stay for longer, you should transfer your coverage through the S1 form. Then, you can choose a public or private insurer.
- Non-EU citizens require valid private health insurance to receive a German visa. Once you arrive, you must take out private insurance until you find employment.
Bear in mind that if your family members are insured, you may be covered by their policy. Check with their provider to find out when this applies.
How does health insurance work for retirees in Germany?
Retirees in Germany with statutory health insurance retain this once they finish working and become members of the pensioners’ health insurance scheme (Krankenversicherung der Rentner – KVdR). Like employees, contributions consist of 14.6% of their pension income – they pay half, while the pension insurance provider pays the other half.
However, the situation changes if you move to Germany during retirement:
- EU citizens with statutory health insurance can transfer this to Germany with the S1 form and apply to a German statutory health insurance fund.
- Uninsured and privately insured individuals and those from outside the EU must take out private health insurance.
German health insurance for students
University students whose parents have German health insurance are usually covered by family insurance until age 25. This is the case as long as they are studying and not earning an income.
International students can use their EHIC or GHIC, if applicable, for emergency care during exchange programs of less than 90 days. In addition, some EU/EEA students can use their current health insurance if Germany has a social insurance agreement with their home country.
Otherwise, students staying long-term in Germany must take out their own insurance. Under-30s can take out GKV at a special student contribution rate of around €90–100 per month plus long-term care insurance of about €30.
Full-time students over 30 can no longer use the student tariff, so PKV is often more affordable. Some insurance companies provide a special rate for students.
In addition, some students can apply for health, accident, and liability insurance through the German Academic Exchange Service (Deutscher Akademischer Austauschdienst – DAAD). Contact your university or visit DAAD online to find out which insurance is suitable for your situation.
Coverage for tourists and short-stay visitors in Germany
For visitors and short stays, EEA and Swiss citizens can typically use their EHIC for urgent care and pre-existing conditions. UK citizens can use their GHIC. Non-EEA citizens should get insurance from a provider with an international scope, such as:
Allianz Care
Allianz Care is a world leader in providing international health insurance. Their various premiums provide professionally designed solutions for a variety of expat lifestyles. So, wherever your life takes you, make sure you have the right health protection for you and your family with Allianz Care.
Bear in mind that it’s still worth taking out travel insurance, even if you have an EHIC or GHIC. This type of policy covers the costs of repatriation, evacuation, and other expenses. Usually, with the EHIC/GHIC and travel insurance, you pay the costs upfront and seek reimbursement afterward.
Asylum seekers and refugees
Asylum seekers and refugees may access healthcare in Germany. However, there are some limitations.
Since 2024, people whose asylum procedures are ongoing can only access emergency medical care during their first 36 months in Germany (up from 18 months previously). You’ll need a voucher (Krankenschein) to visit the doctor, which you can get from your initial reception center or Social Welfare Office. They are valid for three months.
If you are pregnant, you can access regular medical treatment.
After 36 months of residence in Germany, you may receive a health insurance card to access regular healthcare. Additionally, once you have a residence permit, you can take out health insurance like any other German resident.
In addition to limited healthcare, refugees can access specialized support through the following services:
- German Association of Psychosocial Centres for Refugees and Victims of Torture (Bundesweite Arbeitsgemeinschaft der psychosozialen Zentren für Flüchtlinge und Folteropfer – BAfF): provides medical and psychological treatment, support, and protection to refugees who have experienced human rights violations and political persecution.
- Gesundheit ein Mensenrecht: offers contact points across nationwide with information about how uninsured people can access healthcare.
What does German public health insurance cover?
See below for an overview of coverage provided by German statutory health insurance:
| Medical service | Covered? | Notes: |
| Doctors and medical specialists | Yes | |
| Emergency care, hospital visits, and rehabilitation | Yes | Standard stays on a hospital ward are covered. If you prefer a private room, you might want to consider private insurance. |
| Prescription medication and vaccines | Yes | Contraception (e.g., the pill) is covered for people under 20 |
| Mental healthcare | Yes | Because waiting lists are long, it’s often easier to access a mental health professional with private insurance. |
| Maternity care | Partially | Statutory insurance only covers the basic costs of prenatal care. However, most insurance companies will give parents a €100–300 bonus when a new baby is born. |
| Dental care | Partially | These often require co-payments, and there are limitations on what you can claim. |
| Vision care or eye doctors | Partially | These often require co-payments and there are limitations on what you can claim. |
| Sexual and reproductive health | Partially | Complex procedures, such as fertility treatments, require a co-payment. |
| Alternative medicines | Maybe | Depends on your insurer |
| Treatment abroad | Maybe | Depends on your insurer |
| Sick leave coverage (Krankengeld) | Yes | Statutory insurance also covers sick leave. Your employer pays your wages during the first six weeks of your illness, after which the insurance company takes over. They usually pay 70% of your regular salary. In 2026, the maximum sick leave coverage is €135.63 per day and can cover a total of 78 weeks in any three-year period. |
Some public health insurance providers may offer additional services – you can find out what’s covered when applying for a policy. Once you have GKV, your spouse or registered partner and children are also insured.
Although GKV covers the costs of many treatments, there are situations where you may need to make a co-payment. You can read about this in the section on paying for your medical care.
How to apply for state health insurance in Germany
What to do before your move
What you need to do before moving to Germany depends on your situation:
- If you are an EU/EEA citizen, ensure that you have your EHIC to be covered during your transition period.
- If you’re moving for a job, confirm that your employer will register you with health insurance. Also check whether you need additional coverage before your employment contract starts: maybe you’ll need to take out temporary travel or expat health insurance.
- If you’re retired, fill out the S1 form to transfer your benefits from your existing health insurance.
- If you are a high earner or self-employed, or if you don’t qualify for public health insurance, shop around and subscribe to a private health insurance plan, so you are covered as soon as you arrive.
If you’re moving for a job:
- Confirm that your employer will register you with health insurance.
- Check whether you need additional coverage before your employment contract starts.
- If necessary, take out temporary travel or expat health insurance. EU citizens can use their EHIC for emergencies during this transition period.
High earners, self-employed people, and others who don’t qualify for public health insurance will need private insurance (PKV).
How to register for health insurance once you are in Germany
Once you’re in Germany, have secured work, and signed a contract, your new employer will sign you up with a regional insurance company. If you wish to choose your insurance provider, you should do so within two weeks of your start date. Otherwise, your employer may assign you to one automatically.
If you’re self-employed, you must register for health insurance independently. It’s usually a fairly straightforward process that involves completing an online form and signing electronically.
After registering, your health insurer will issue you a health insurance card (Gesundheitskarte) or EHIC (Europäische Krankenversicherungskarte). You must show this each time you visit a new doctor or specialist.
What documents will you need to register for German health insurance?
You’ll need several important documents to register for statutory health insurance in Germany. These vary slightly depending on your employment or study status, but the core documents are generally the same.
All applicants require:
- A valid ID: a passport or national identity card
- Proof of residency: documentation showing your registered address in Germany, usually a registration certificate (Meldebeschinigung) from your local citizens’ office (Bürgeramt)
- Bank details: you typically require a German bank account to set up automatic payment for contributions.
Additional documents depend on your status:
- Employees: Your employer will handle most of the application process with the health insurance provider. However, you usually need to provide your employment contract to complete your registration.
- Self-employed individuals: You may require more in-depth financial information. This includes documents such as an income tax assessment or business analysis to determine your income level and potential contributions. Contact your chosen insurer to find out the specific documents they need.
- Students: Both home and international students must show a certificate of enrollment from a German university.
- Pensioners: You must submit information about your pension status and income to determine your contributions – check with your insurer to confirm the specifics.
- Unemployed individuals receiving benefits: You’ll likely need to provide an employment benefit notice (Arbeitslosengeldbescheid) from the German job center. If you’re moving to Germany as a jobseeker from the EU or EEA, you’ll need proof of previous insurance coverage or benefits – you can use the S1 form to transfer these.
Always check with your chosen health insurance provider to confirm the necessary documents for your application.
Electronic medical data card (elektronische Gesundheitskarte – eGK)
Once you have registered for statutory health insurance, your health insurance provider will issue you an electronic medical data card (elektronische Gesundheitskarte – eGK). The card shows your name, your insurance provider’s name, and your personal ID numbers. For individuals over 15, it also includes a photo for identification.
The eGK contains a chip that stores key personal information, including:
- Your name
- Address
- Date of birth
- Gender
- ID number
- Insurance status
- Dates of your health insurance coverage
This health card also functions as your EHIC, allowing you to access healthcare services when traveling in the EU and certain other countries.
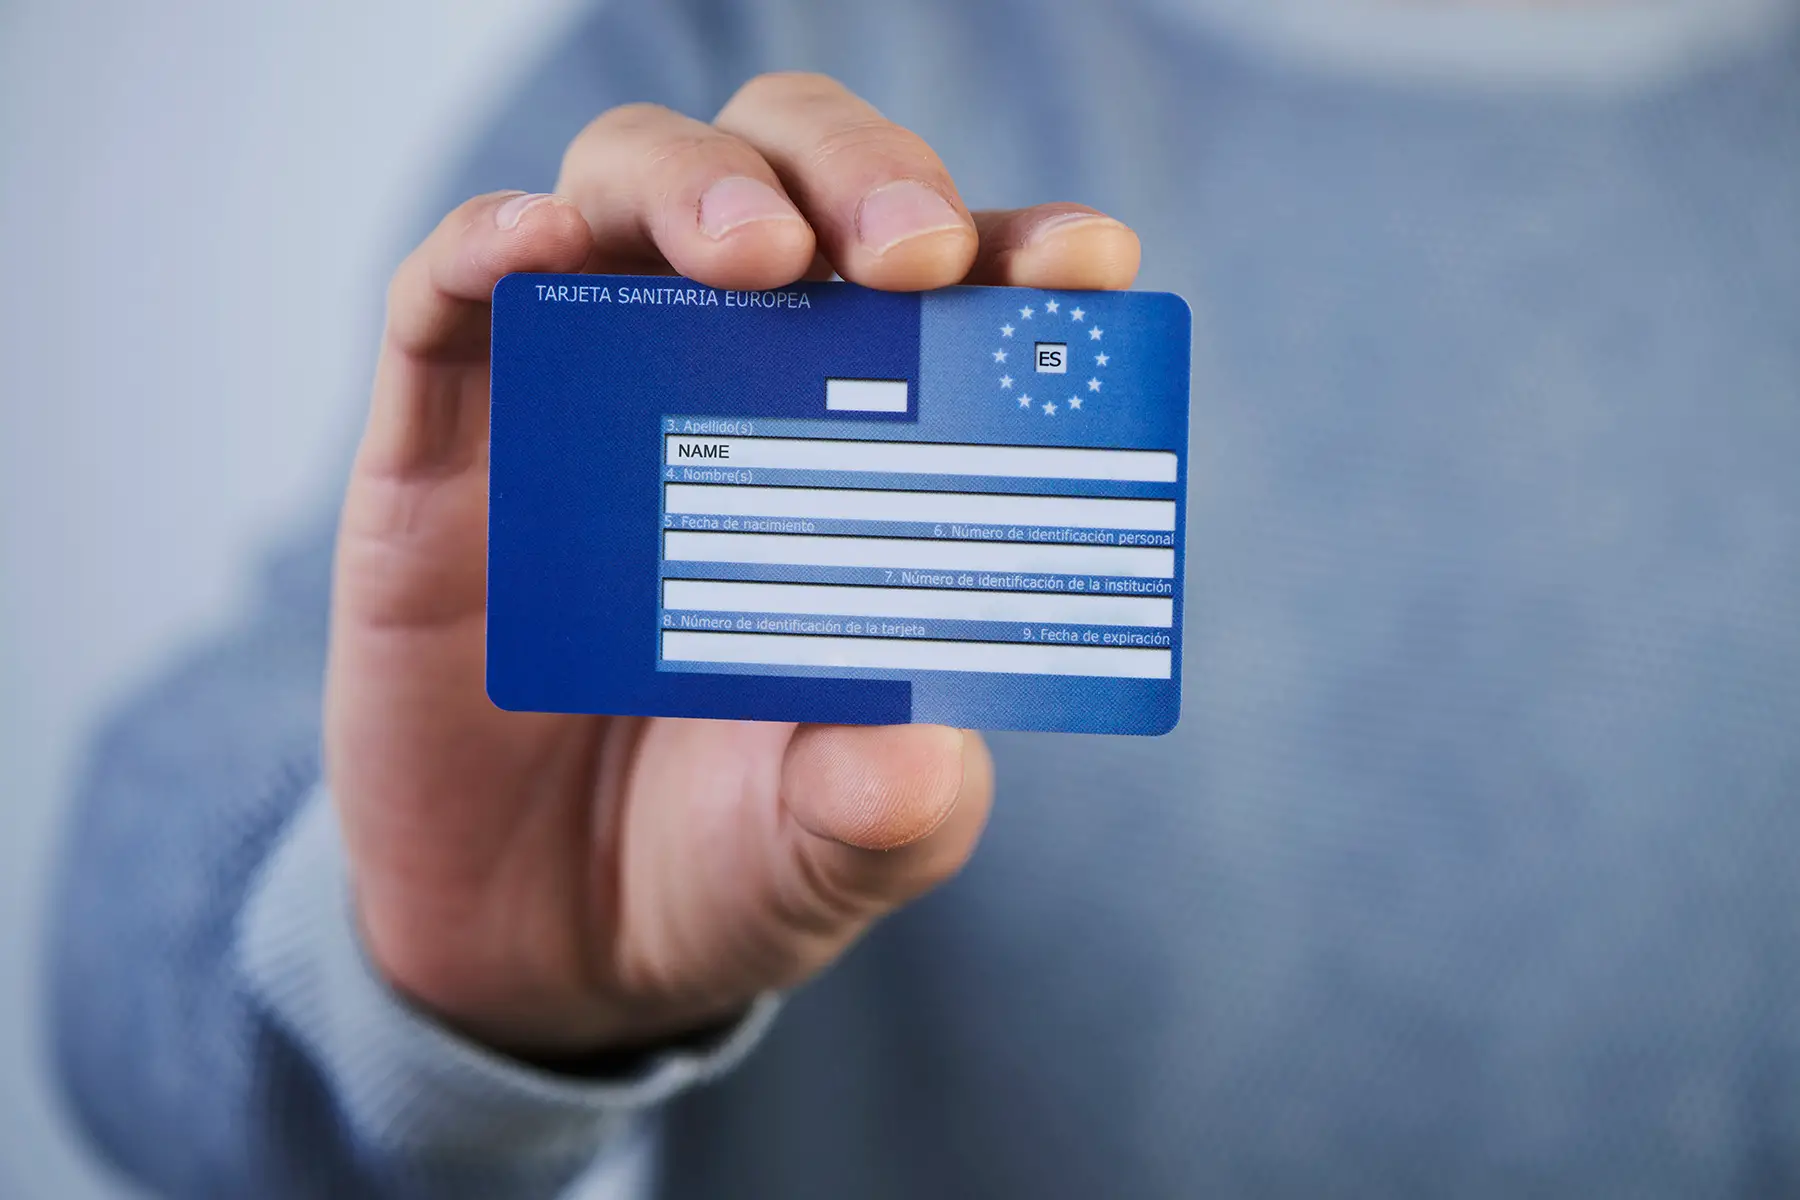
You use this card to access medical treatment by presenting it at your doctor’s office or other healthcare provider during your visit. It allows the provider to bill the insurance fund directly for your treatment.
The eGK is valid for five years, and you will receive a new one from your health insurance provider automatically before it expires.
Paying for your medical care with health insurance in Germany
If you have statutory health insurance, your medical care is billed directly to the insurer. While you might receive a copy of the bill, the insurer covers the costs. However, there are some cases where you’ll need to make a co-payment (Zuzahlungen), such as certain medications (10%).
You may need to make these co-payments upfront or receive a bill later. They are generally affordable and should never exceed 2% of your annual income.
There are also exceptions to co-payments for people who are chronically ill and require extensive medical treatment or prescription drugs. In cases of reduced earning capacity due to a medical condition, the healthcare system sets a co-payment limit of 1% of gross annual income.
German private health insurance (PKV)
Approximately 10% of German residents are covered by private health insurance (private Krankenversicherung – PKV) instead of GKV. The following groups are eligible for PKV:
- Employees earning over €77,400 per year (2026)
- Self-employed people and freelancers
- Students over 30
- Civil servants
International residents, including non-EU citizens, can also take out private health insurance if they meet the eligibility criteria.
Civil servants frequently choose private health insurance, as PKV is typically more affordable than statutory insurance – the cost depends on the level of coverage needed rather than their income.
What if I’m not eligible for public health insurance and can’t afford private?
Those on lower incomes who are not eligible for GKV may also take out private health insurance via the Basistarif. This basic level of health insurance provides similar coverage to GKV, but premiums are capped at the maximum GKV contribution rate. The Basistarif ensures that everyone has access to insurance, regardless of income or status.
Benefits of using private health insurance in Germany
Private health insurance can offer several advantages, particularly if you’re a high earner or looking for more personalized care. Key benefits include:
- Cost-effectiveness: Private insurance can be cheaper than statutory coverage if your earnings are above a certain threshold.
- Improved accessibility: Access to specialist treatment, often with English-speaking doctors
- No co-payments: Many private plans eliminate the need for additional payments.
- Shorter waiting times: Faster appointments and treatment compared to public insurance
However, be sure to check that pre-existing conditions are covered and the terms for switching providers. Bear in mind that it can be challenging to swap back to the public healthcare system after opting for PKV.
International health insurance for expats in Germany
In addition, some expats may find international health insurance particularly useful. These plans provide global coverage, including in Germany. These policies allow you to find coverage that suits your needs, usually with English-speaking support.
When moving to Germany, an international health insurance plan can cover you while you organize your statutory health insurance. It’s also an option if you are not eligible for GKV. For example:
- Non-EEA expats and immigrants coming to Germany to work or study must prove they have appropriate private coverage before they can enter the country.
- Unlike those coming on a work visa with a contract in hand from a German employer, most internationals will not have healthcare coverage during the first three months of their stay.
- Finally, as seen above, certain categories of internationals will not qualify for public healthcare at all, making private insurance essential.

Senior Editor
Sarah Fairman
Insider Tip
Some German health insurance providers offer perks, like money off dentist appointments, gym memberships, and preventative health screenings. It’s worth comparing these benefits when choosing an insurer.
How do you apply for private medical insurance in Germany?
To apply for private health insurance in Germany, you can usually sign up directly with an insurance provider.
The cost of the plan is based on your individual medical needs rather than your income, so you typically require a medical assessment.
If you are not eligible for public healthcare but do not meet the medical requirements for private coverage, you can still take out a basic plan (Basistarif) from a private insurer.
Cigna Global
Enjoy peace of mind while living in Germany with Cigna Global’s long-term international health insurance plans (12+ months). Get tailored coverage, direct billing with many providers, complex case management, and global care on demand, with access to a network of 1.5+ million doctors, specialists, and therapists.
Private insurance – contributions and reimbursements
PKV contributions and reimbursement work differently from statutory health insurance. Contributions usually depend on how private insurance makes up your coverage:
- Private health insurance as a primary plan: Employees eligible for private health insurance have their employer cover half of their premium, up to the maximum contribution rate set by the statutory insurance system. This amounts to €508.59 per month in 2026.
- Supplementary private insurance: if you have taken out private coverage to supplement your statutory insurance, your employer generally won’t subsidize it.
- Corporate health insurance: Some employers offer corporate health insurance (betriebliche Krankenversicherung – bKV), which provides supplementary coverage for additional healthcare services. As it is intended to complement existing healthcare, it doesn’t follow the same cost-sharing rules as primary health insurance – generally, the employer covers the costs.
Unlike GKV, where payments are made directly by the insurance fund, PKV operates on a reimbursement model. This means that you, as the policyholder, pay for medical services upfront and submit the invoices to your private insurer for reimbursement.
Private and international health insurance providers
There are many different private health insurance companies in Germany that offer a wide array of plans to fit different budgets and lifestyles.
Here are some of the local private health insurance companies in Germany providing expat-friendly policies:
- DA Direkt – provides supplementary dental insurance
- Embea – covers critical healthcare such as heart attacks and cancer
- Feather – customizable coverage, with full English-speaking support
For expats not (yet) eligible for a private policy, some of the largest international health insurance companies that operate in Germany as well as globally include:
If you need help choosing a health insurance plan, it may help to consult a broker who can guide you through the process. Several brokers in Germany specialize in assisting internationals with organizing their health insurance and other coverage, including KLforExpats.
The Munich-headquartered financial services company offers international health insurance plans for expatriate students, professionals, couples and families. Depending on the policy, Allianz Care covers everyday medical expenses, emergency treatment, dental consultations, maternity, surgery, and outpatient fees.
The American health services company serves expats and globally mobile individuals in more than 200 international jurisdictions. Cigna Global’s policies are easily customized to coverage and cost requirements and customers can pick from three coverage levels, modular plans, and several cost-share options.
How much does German health insurance cost?
Although German healthcare is generally affordable, it’s not free. Health insurance fees are part of your social security contribution and are deducted from your salary before it even gets to your bank account.
The statutory health insurance (GKV) contribution is 7.3% of your gross income, with your employer matching this amount. Together, the contributions equal 14.6% of your income.
Some public insurers also charge an additional contribution, which can fluctuate year-to-year depending on healthcare expenditure. In the first half of 2025, the average additional contribution rate across all public insurance companies was 2.9%.
For those opting for private health insurance (PKV), the cost of premiums depends on factors like age, health, and coverage level. The average private healthcare premium was €529 per month in 2025.
It’s always advisable to research and compare plans before moving to ensure you find the best health coverage to suit your budget and needs.
Useful resources
- Association of Psychosocial Centres for Refugees and Victims of Torture (BAfF) – support for migrants who have experienced violence and exile
- Federal Ministry of Health (Bundesministerium für Gesundheit) – government ministry responsible for healthcare
- Gesundheit ein Menschenrecht – information on healthcare for uninsured people
- GKV Spitzenverband – German agency in charge of statutory health insurance
- Künstlersozialkasse – social security support for self-employed artists and journalists
- PKV Association – information and news about private health insurance in Germany


Did you find this guide helpful?