


Finance
Insurance
Car insurance in Germany
Planning on driving a vehicle in Germany? Find out what types of coverage you need with this handy guide to car insurance in Germany.
Germany has a strong automobile industry and main residents own and drive cars on a regular basis. As in other European countries, you will need to be covered by a minimum level of car insurance in Germany and will also be able to choose optional extras. This guide covers everything you need to know about car insurance in Germany, including types of coverage, costs, and application processes. As you prepare for your move, remember that managing finances across borders can be challenging – services like Wise can help you transfer money to Germany with the mid-market exchange rate, making it easier to set up your new life including paying for essentials like car insurance.
Our guide explains everything you need to know, with information on:
MW Expat
Planning to drive in Germany? Get your mandatory third-party vehicle insurance from MW Expat. Their range of insurance options meets Germany’s requirements while ensuring comprehensive protection for your car and peace of mind on the road. Save 45% compared to the market average with a plan from MW Expat.

Car insurance in Germany
Car insurance (Kfz versicherung or autoversicherung) in Germany is compulsory for all drivers. If you drive in Germany, you will need a minimum of third party liability insurance on your vehicle in order to get it registered and get a German license plate. Insurance certificates must be displayed in the vehicle at all times.
Germany has one of the biggest auto insurance markets in Europe and the largest overall motor market on the continent. There are around 90 vehicle insurance companies in the country according to 2016 statistics from Insurance Europe. These include:
One way to make dealing with German car insurance a little easier is to work with an international-friendly broker such as Versicherungsbüro Weiss, who specialize in helping newcomers to Germany with their coverage.
As with many European countries, you need to insure the vehicle rather than the driver in Germany. However, some comprehensive policies allow insurance of multiple drivers for the same vehicle.
Many German insurers allow second vehicle insurance on the same policy. Because of this, parents in Germany can insure vehicles belonging to their children as the second car on their policy.
The Federal Financial Supervisory Authority (BaFin) regulates the German insurance market and most companies belong to the German Insurance Association (Die Deutschen Versicherer – GDV)
Can you use car insurance from another country in Germany?
Drivers from EU/EFTA countries can use insurance from their home country. Those from outside the EU can sometimes use insurance from their home country if they have an international green card.
However, long-term residents in Germany will need to take out a German insurance policy.
If you’re temporarily visiting Germany with a car registered abroad, your home insurance policy may cover you through the Green Card system. However, if you’re becoming a resident, you’ll need to register your vehicle in Germany and obtain German insurance.
When managing insurance policies across different countries, be mindful of currency conversion costs. banks often add hidden markups to exchange rates when transferring money internationally. Using Wise can help you avoid these hidden fees by offering the mid-market exchange rate when transferring money to pay for your German insurance premiums.
Types of car insurance in Germany
There are three main types of German car insurance: third-party, partial coverage, and comprehensive.
Third party
Third-party (Haftpflicht) insurance is the minimum level of coverage required for drivers in Germany. It covers damage to other vehicles in the event of an accident, including medical costs. However, it doesn’t cover any of your own costs.
Partial cover
Partial cover (Teilkasko) covers everything included in third-party coverage plus some costs related to damage to your own vehicle, including theft plus fire and storm damage. However, it does not cover vandalism or any costs relating to accidents that are your fault.
Comprehensive
As suggested by its name, comprehensive insurance (vollkasko)covers full costs including damage to your own and other vehicles in incidents that are your fault. Some vollkasko policies also cover additional costs such as those relating to disability and death resulting from the accident.
Because of the breadth of coverage, this policy is the most expensive type. Some dealerships for new cars insist on this as a minimum level policy.
Car insurance costs in Germany
As in other places, car insurance costs in Germany are based on a number of different factors including:
- driver age;
- driver experience and record;
- vehicle value;
- number of drivers insured;
- location (costs for bigger cities are usually more expensive);
- vehicle use (including purpose of use and how frequently you will drive)
You can reduce your annual premiums in various ways, including paying a higher excess/deductible (the amount you pay towards any claim), paying the annual amount in full, or reactivating your no claims bonus.
Because of the various factors involved in cost calculation, insurance premiums in Germany can vary rapidly from around €100 a year for third party coverage for cheaper or second-hand vehicles to over €1,000 a year for comprehensive coverage on top-range models.
Additional forms of car insurance in Germany
You can take out optional extra forms of car insurance in Germany. Most insurance companies will offer various add-ons including:
- Breakdown insurance – this covers the costs of your car being towed away in the event of a roadside breakdown. It also sometimes includes replacement vehicle costs and the costs of transporting ill or injured people.
- Legal insurance – covers legal expenses in the event of an incident that goes to court.
- Additional equipment coverage – if you carry or store expensive equipment in your vehicle, you can cover the costs of damage or theft if you pay a higher premium.
- Extended elementary damage – if you live or travel near mountainous areas, you may need this to protect against the risk of damage due to avalanches or extreme snowfall.
- Rental car insurance – rental companies usually provide minimum cover for their vehicles, but additional coverage can afford you extra protections against costs. Companies offering this in Germany include Allianz Travel.
Car insurance bonuses and penalties in Germany
Germany has a no-claims bonus system (schadenfreiheitsklasse) which entitles drivers who have gone a year or more without making any claim to a discount on their annual premium.
Exact discounts can vary between insurers but as a rough guide you will be entitled to:
- Up to 35% off annual costs if one year without making a claim
- Around 45% off if three years without making a claim
- Approximately 50% off if five years without making a claim
- Up to 80% off if 15+ years without making a claim
You can often carry over no claims periods from other insurance companies, including companies from abroad. If you are moving to Germany from overseas and want to transfer a no-claims bonus, it is a good idea to request a letter from your previous insurer attesting to your no-claims period.
Companies also often penalize drivers with a poor driving record. Expect to pay an increased premium if you:
- are a young or inexperienced driver;
- have been in an accident where you were at fault;
- have any points on your license for violations such as speeding or drink driving
AXA
Looking for car insurance in Germany? Give yourself peace of mind when you get behind the wheel with AXA. Their customizable premiums can be tailored to suit your driving needs, ensuring you get the best coverage for your vehicle. If you’re looking for coverage before you hit those famous German autobahns, see how AXA can help.
Car insurance companies in Germany
There are around 90 car insurance providers in Germany so it pays to shop around for the best deal. Some of the most popular companies include:
You can compare insurance policies from German companies by using comparison websites such as Verivox or Joonko.

How to choose car insurance in Germany
You can take a number of different factors into account beyond the premium costs when shopping for car insurance in Germany. These might include:
- No-claims bonus – what discounts are offered and what is the policy around transferring bonuses from elsewhere?;
- Policy coverage – what is excluded from standard coverage, can this be added on if necessary and at what cost?;
- Excess/deductible options – what is the mandatory excess and what are the options for choosing to increase it?;
- Company reputation – how does the company perform in reviews and what is the customer feedback like?;
- Claims process – how straightforward is it, what is involved and what do the reviews say about how it works in practice?;
- Roadside assistance – does the company offer a good breakdown assistance policy?
How to apply for car insurance in Germany
To take out German car insurance, you will need to provide:
- your German driving license number
- personal ID
- other personal information relating to your driving history
- German bank account details (if paying by direct debit)
- documents relating to vehicle purchase (some insurers may ask for these)
Most insurance companies allow you to purchase an insurance policy online. If you do this, you should receive your insurance details electronically within 24 hours.
Upon purchasing auto insurance, you should receive:
- Your EVB insurance number (elektronische Versicherungsbestätigung) and insurance policy information
- EU accident statement form to use in the event of an accident
How to make a car insurance claim in Germany
If you need to make a claim with your insurer, you should contact them as soon as possible. Claims relating to accidents should be filed within two weeks of the accident. You should:
- Exchange details with the other party or parties involved in the accident
- Take pictures of any damages
- Take contact details of any witnesses to the incident
- Fill in the accident report form to submit to your insurer;
- Call the police only if the accident has resulted in serious injuries or if the other party is not present (e.g., if you have crashed into a parked car or someone else’s property and caused extensive damage)
- Call an ambulance if anyone is seriously injured and needs hospital treatment
You will need to send the relevant information to your insurer and they will let you know if you need to provide any more information. Claims should be resolved within three months. The insurer usually sorts costs out directly with companies involved (e.g., auto repair garages).
If you need to file a claim with the other party’s insurer and they don’t provide you with insurance details, you can find them by providing the license plate number to the Central Office of Car Insurers. This central office can also provide you with necessary details of insurance claims representatives in other EU member states should you be involved in an accident in another EU country.
Canceling a contract or changing provider
Beware as many German car insurance contracts renew automatically. You usually need to provide at least one month’s notice if you wish to cancel a contract or switch to another provider.
You can terminate an insurance contract early under exceptional circumstances. These include:
- increased premiums. The insurance company is obliged to provide at least one month’s notice for any premium increases. Most policies in Germany run from 1 January so you should receive notification of increase no later than 30 November.
- if you are not happy with your insurer’s handling of a claim. You will need to provide details in writing. If the insurer contests this, you may need to go through a formal complaints procedure.
- sale of vehicle. The purchaser of the vehicle automatically takes on the existing policy but has the right to cancel as long as they can confirm purchase of coverage with another insurer.
Making a complaint about a car insurance company in Germany
German auto insurance companies must accept car insurance applications under the Compulsory Insurance Act (Section 5/2). However, there are instances where they can refuse to offer a policy, such as if the applicant has previously taken out a policy with them and violated the terms of the contract.
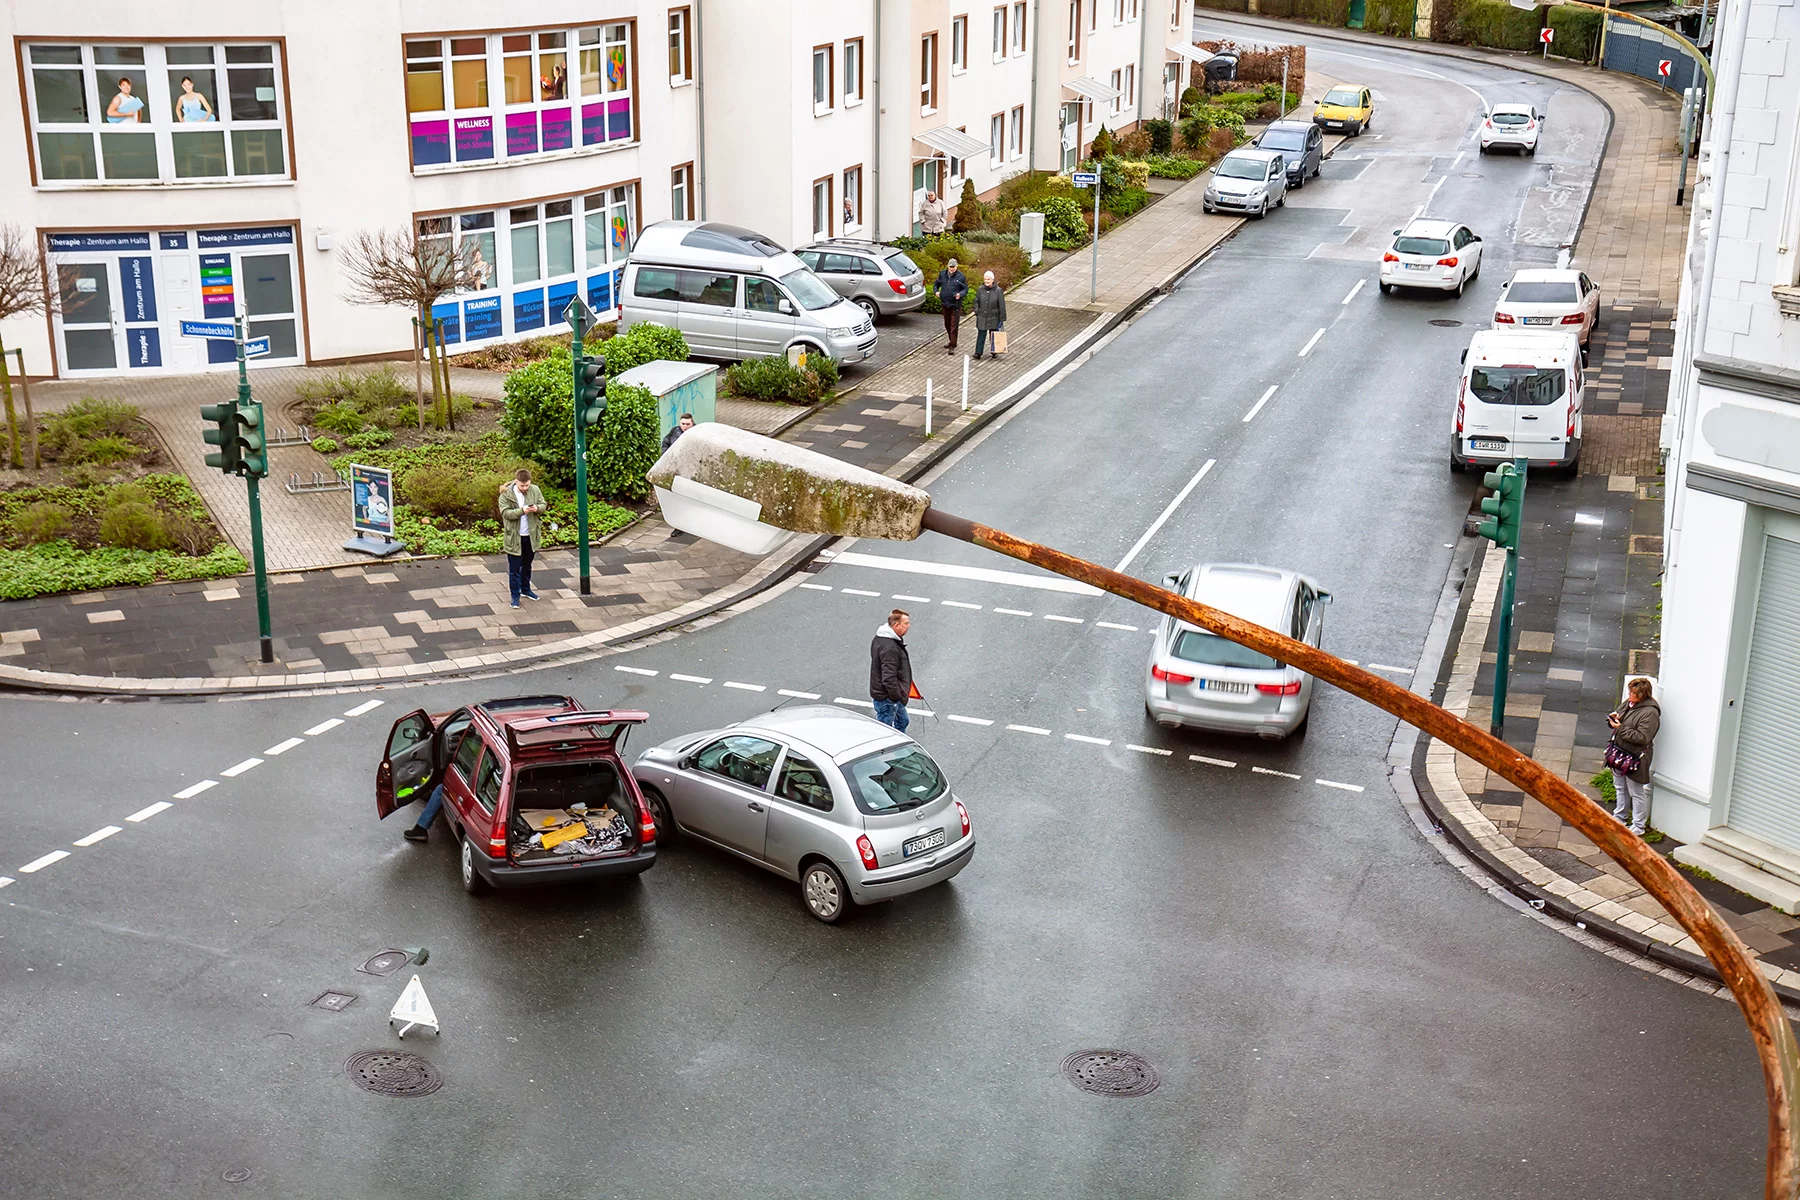
If you feel that a car insurance company in Germany has treated you unfairly, or you are not happy with their services, you can file an official complaint. The procedure for doing this is:
- write to the complaints department of your insurer in the first instance.
- if you receive no reply or are unhappy with the outcome, you can escalate the complaint to BaFin.
- you can also complain via the Insurance Ombudsman for an independent and free out-of-court resolution.
- if you are still not happy with out-of-court outcomes, you can take the case to court. However, this means that you will be responsible for your own legal fees.
Roadside assistance in Germany
ADAC (Allgemeine Deutsche Automobil-Club) and AvD (Automobil-Club von Deutschland) are the two main automobile clubs offering national breakdown and recovery services. Basic membership costs for ADAC are €54 a year, with more expensive premium membership offers also available.
German highway assistance can be called free of charge from emergency phones alongside the roads. If you’re involved in an accident, call the police on 110 or call 112 for an ambulance. In addition to this, don’t forget that it’s illegal to leave the scene of an accident without getting help.
Useful resources
- BaFin – German Federal Financial Supervisory Authority, which regulates insurance companies in Germany
- Central Office of Car Insurers – provides information on insurance in the event of an incident. You can find details on a vehicle’s insurance policy if you provide the license plate number.


Did you find this guide helpful?