


About Thailand
Transportation
Car finance in Thailand for expats: how to get a car loan (2026)
Securing car finance in Thailand as an expat is certainly doable, though the path to approval feels a bit unpredictable. Lenders generally look for a Non-Immigrant visa, steady Thai income, and local paperwork before handing over the keys. However, bank branches and dealerships may apply these rules differently, meaning a setup rejected in one office may pass in another.


This guide breaks down the eligibility checks, required paperwork, and key approval routes to help you navigate the process. We will also cover the smartest ways to move your funds into Thailand for deposits and monthly repayments without losing money to hidden exchange fees.
Key takeaways
- Employed expats with a Non-Immigrant visa, work permit, Thai salary history, and a clear local address trail are usually in the strongest position.
- Buying a car and financing a car are different steps. You may be allowed to own the vehicle but still fail the lender’s credit check.
- The core paperwork usually includes your passport, visa, residence proof, income evidence, Thai bank statements, and vehicle details.
- A Thai guarantor may still be requested, especially if your local income history is short, your visa status is weaker, or the car is older.
- Dealer-arranged finance can be easier for first-time expats because the showroom often knows which lender partner and branch may consider foreign applicants.
- If you are funding a deposit or car repayments from abroad, compare the full transfer cost and timing before the due date.
International money transfers with Wise
For convenient cross border transactions with transparent fees, check out Wise.
Expats can use Wise to hold and exchange Thai Baht (THB) and 40+ other currencies with transparent fees at the mid-market exchange rate. The Wise card allows you to spend in 150+ countries, while the account lets you send money to 160+ countries and receive payments in multiple currencies including THB and USD.

Can expats get car finance in Thailand?
Yes, some expats can get car finance in Thailand, but lenders usually want stronger proof than they would from a lower-risk local borrower. Visa type, work permit status, Thai income, address history, deposit size, and the age of the vehicle can all affect the answer.
However, even if you can’t get financing, that doesn’t stop you from purchasing a car. Some expats can legally buy or register a vehicle while still struggling to secure credit, because the lender is judging repayment risk rather than ownership rules.
Most lenders look for a specific set of criteria before considering an expat application:
- Long-stay visa or another clear legal basis to remain in Thailand
- Stable income, ideally paid into a Thai bank account
- Proof of residence that matches your other records
- Enough cash for deposit, fees, insurance, and the first instalment
Who is most likely to qualify?
Long-term expats with a Non-Immigrant visa, work permit, Thai salary deposits, local bank statements, and stable residence proof are usually in the strongest position. An employed expat with six months of salary landing in a Thai account and a recent Certificate of Residence will often look safer to a lender than a newly arrived remote worker paid overseas.
Lenders typically consider the following profiles to be the strongest candidates:
- Non-Immigrant visa or other long-stay status
- Work permit, if your route requires one
- At least six months of local salary evidence
- A Thai address backed by current paperwork
What can make approval harder?
Tourist visas, overseas-only income, a short time spent in Thailand, and thin local banking history all raise questions. Approval can also get harder when the car is older, the seller is private, the deposit is small, or the dealer has no strong relationship with a lender that will assess foreign borrowers.
Applications usually face friction when one or more of these hurdles crop up:
- Tourist visa or very short remaining permission to stay
- Remote income paid abroad with no Thai salary trail
- No Thai guarantor where one is requested
- A branch or dealer that has little experience with foreign applicants
Documents you will usually need
The exact pack varies, but most expats should prepare finance documents before they start comparing cars. Loan approval paperwork, ownership transfer paperwork, and later registration paperwork overlap, but they are not identical.
A lender will usually focus on identity, residence, income, and repayment capacity first, meaning you’re likely to need the following:
- Passport and current visa pages
- Work permit, if applicable
- Certificate of Residence or other accepted address proof
- Recent payslips or an employer letter
- Thai bank statements, often covering six months
- Vehicle quotation or sale details
- Copies of any guarantor documents, if requested
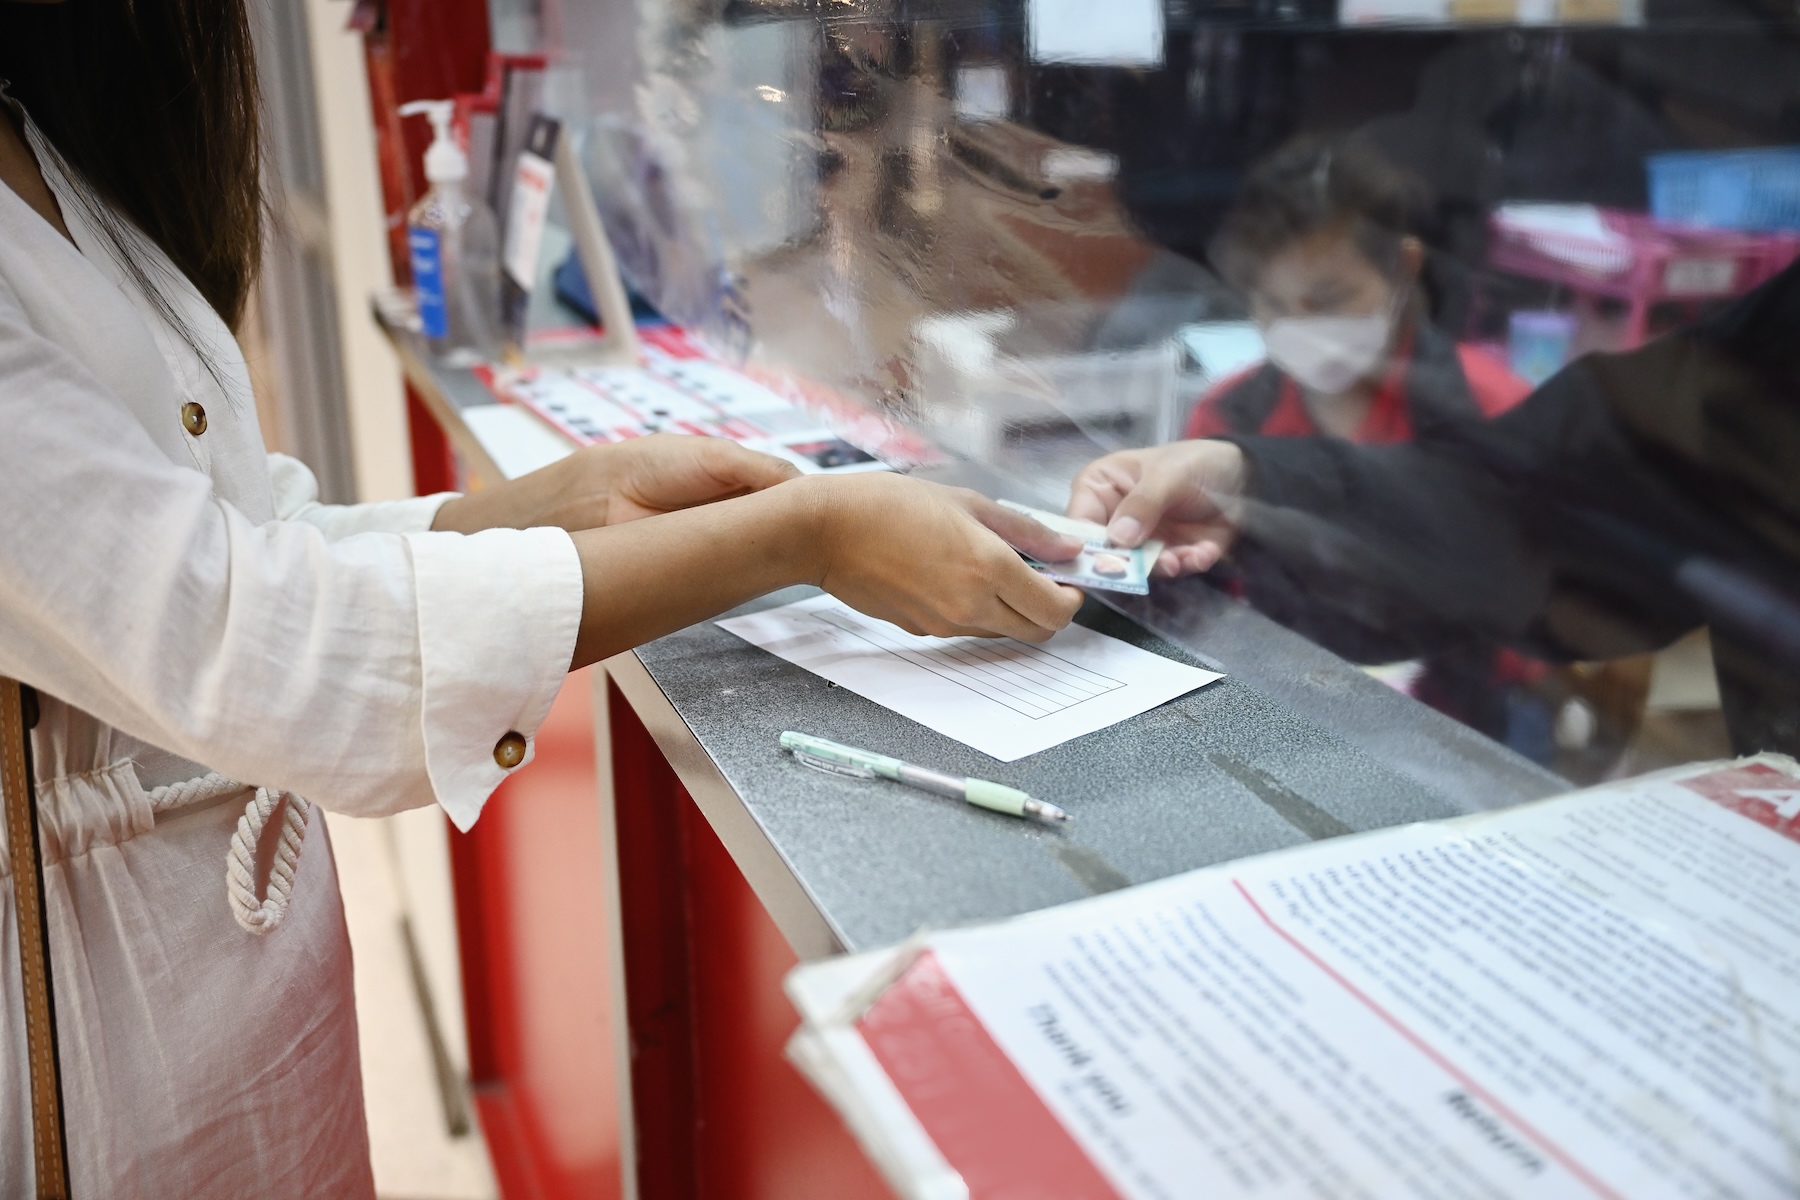
How to prove residence and income
Residence proof is where many expats lose time. The Immigration Bureau’s address and stay-admin systems, including TM30 reporting, mean lenders often want residence evidence that matches the rest of your file.
- Certificate of Residence from immigration or another accepted official source
- TM30-related address trail, where relevant to your stay
- Rental agreement and matching local address records
- Thai salary slips or an employer letter
- Local bank statements showing salary or regular income
A fresh address document and clearly matching bank and employment records can save a wasted trip, because some lenders reject old or inconsistent paperwork even when the application profile looks strong.
How car finance in Thailand usually works
In most cases, you choose the car first, then check whether the dealer has a finance partner that will assess your profile. If you go to a bank first, you may get clearer borrowing terms, but many expats find the showroom route more practical because staff already know which lender or branch may be open to foreign applicants.
Once you submit documents, the lender reviews income, residence, vehicle type, and sometimes the guarantor. If approved, you pay the deposit, sign the hire-purchase agreement, arrange any required insurance, and then move on to ownership transfer and registration.
Choose the car and confirm whether it is new, used, dealer stock, or a private sale.
Check lender routes before paying any reservation or deposit.
Submit your documents and wait for the credit decision.
Review the deposit, instalment, fees, and guarantor conditions.
Sign the agreement only after the vehicle and seller checks are clear.
Then complete transfer, registration, and payment setup.
Deposits, terms and Thai guarantors
Foreign applicants are often asked for more cash up front than a lower-risk Thai borrower, especially on used cars or weaker visa profiles. Terms can also differ between new and used vehicles, and some lenders still ask for a Thai guarantor. On Krungsri’s published used-car page, foreign applicants are listed as needing a passport, a work permit with enough validity, and a Thai-national guarantor.*
| Issue | What often changes | Why it matters | Where to verify |
| Deposit | New or used car, income profile, branch view | More cash up front can change affordability | Dealer quote and lender page |
| Term | 12 to 84 months depending on the product | Longer terms cut instalments but raise total cost | SCB and Krungsri product pages |
| Guarantor | Some lenders require one for foreign applicants | A missing guarantor can stop approval | Branch, dealer partner, or written criteria |
*Checked on 24th September 2026.
Where expats can look for car finance
Major institutions like Bangkok Bank, Kasikornbank (KLeasing), Krungsri, and Siam Commercial Bank (SCB) are usually the first stops for expats searching for auto finance. Personal loans can also work as a fallback when a vehicle loan falls through.
However, official websites do not always reflect real-world requirements for foreign applicants, making branch visits necessary. SCB, for example, provides English pages for auto loans, whereas KLeasing’s published eligibility criteria for private individuals require Thai nationality, alongside a national ID card and a guarantor’s documents, with no separate foreign-applicant provision listed. Confirming policies directly with a branch manager or dealership financing officer is essential before applying.
| Route | Best for | Strength | Likely friction | How to verify |
| Major local banks | Employed expats with Thai income and a clear paper trail | Published product pages and a broad branch network | Expat handling can still vary by branch | Ask the branch which foreign-applicant documents it accepts |
| Dealer-arranged finance | First-time buyers at authorised showrooms | Staff often know lender partners already used for expats | The easy route can still cost more overall | Ask for the full repayment schedule in writing |
| Used-car specialist finance | Buyers using a tent or used-car dealer | More practical for used stock | Car age, seller route, and guarantor risk can tighten criteria | Check age limits and appraisal rules first |
| Personal-loan-style fallback | Strong earners rejected for standard auto finance | Can widen your options | Higher total cost and fewer car-specific protections | Compare the total repayable amount, not just approval odds |
Major local banks vs dealer-arranged finance
Choosing between a bank and showroom finance comes down to identifying which route offers a realistic approval path without hidden costs. Applying directly through a major bank often brings clearer underwriting criteria and published rate tiers. Dealer-arranged finance can feel more straightforward because sales teams already maintain established relationships with specific local finance branches experienced in processing expat applications.
Consider these practical realities when weighing your financing options:
- Direct bank routes favor strong local paperwork: Banks typically offer competitive rates to expat applicants who can supply a valid work permit, tax receipts, and consecutive Thai bank statements showing a stable salary.
- Dealer finance leverages local branch relationships: Showrooms can often route your application to specific finance managers who understand how to handle foreign passports and guarantor setups.
- Used-car financing depends on vehicle age: Financing an older second-hand car brings higher interest rates and stricter down payment demands regardless of whether you apply through a bank or a dealer.
- Flat rates hide the true cost of borrowing: Thai car loans are routinely quoted in flat interest rates. Always compare the total repayable amount across the entire term rather than relying on headline percentages.
- Convenience should never override total repayment costs: A dealer handling the paperwork on-site is only a win if the combined interest, mandatory insurance packages, and processing fees line up with standard bank offers.
If you expect to receive salary locally or set up auto-debits for repayments, Expatica’s How to open a bank account in Thailand in 2026 guide covers the banking side of that workflow.
How to compare the real cost of a loan
The headline rate is only one part of the borrowing cost. A lower flat rate does not always mean a cheaper deal if the deposit, fees, insurance, or term length change the total amount you repay.
SCB’s published auto-finance pages are useful here because they show both flat and effective pricing for new and used cars. That is a good reminder to compare like with like, especially if you will also be converting money into THB each month.
- Deposit required, not just the monthly instalment
- Flat rate versus effective rate
- Total repayable amount across the full term
- Insurance, admin fees, and dealer add-ons
- Early-settlement rules and transfer or exit fees
- Your final THB cost after any monthly currency conversion
How to fund deposits and monthly repayments from abroad
Funding car deposits or monthly instalments from abroad usually means converting foreign currency and getting Thai Baht into a local account well before your payment deadline.
If you already hold a local Thai bank account, this is mostly a routine top-up process. Comparing standard bank wires against international transfer services like Wise makes sense for both large initial deposits and recurring payments, since providers show conversion rates and fixed fees upfront rather than hiding them in the exchange rate spread. Just build in a few buffer days for identity checks or higher-value transfer approvals to clear before your due date.
- Confirm the Thai receiving account details and your loan due date.
- Check the full transfer cost, including the exchange rate and any transfer fee.
- Send the money early enough for checks, weekends, and cut-off times.
- Top up the Thai account before the instalment date rather than on it.
For wider context, Expatica’s International money transfers in Thailand guide explains the transfer landscape in more detail.
Common pitfalls to avoid
Most problems happen after the first inquiry. The common mistake is treating one successful expat anecdote as a rule that applies to every visa type, branch, and used-car deal.
- Check lender policy against your visa and income profile before you shop seriously
- Confirm the lender route before paying any used-car deposit
- Keep finance paperwork separate from blue-book and transfer documents
- Budget for insurance, admin, and registration costs, not just the instalment
- On a used car, verify ownership, blue-book status, and any outstanding finance before money changes hands
FAQ
Frequently asked questions about car finance in Thailand
Can foreigners get a car loan in Thailand? 
Yes, but a foreigner car loan application in Thailand is usually assessed more strictly than a standard local case. Lenders often look at visa status, work permit or income profile, Thai bank history, residence proof, deposit size, and their own branch policy.
Do expats need a Thai guarantor for car finance in Thailand?
Sometimes. Some lenders may ask for a Thai guarantor, especially for foreign applicants, used-car finance, or thinner local income records, while others may lean more on deposit size and overall file strength.
Can you finance a used car in Thailand as an expat?
Yes, used car finance expat routes do exist, but the rules are often tighter. Vehicle age, resale value, dealer route, and proof that the car is free of outstanding finance all matter more on a used purchase.
Can you get car finance in Thailand on a tourist visa?
Usually not through mainstream routes. Tourist visas rarely give lenders enough comfort on long-term stay, local address stability, or predictable repayment, so you should verify directly with the branch instead of relying on anecdotal exceptions.
How much deposit do expats usually need for car finance in Thailand?
There is no single expat deposit figure. The car loan deposit lenders ask for in Thailand depends on the lender, the branch, your profile, and whether the vehicle is new or used, but foreign applicants may be asked for more up front.
How can you pay a Thai car loan from abroad?
A common route is to fund a Thai bank account or other eligible receiving account from overseas before the due date. Wise is one option to compare if you want upfront fee visibility and a straightforward way to move money for deposits or recurring car repayments.
Useful resources
Did you find this guide helpful?