


Finance
Banking
Mobile banking in Austria
Mobile banking in Austria may still be in its infancy, but for expats who want to easily manage their money, here is everything you need to know.
Being a rather conservative country, it is perhaps not surprising that the majority of people in Austria still prefer to use cash and traditional banks rather than digital banking. That said, the sector is gradually growing with the emergence of mobile banks and mobile banking apps.
For expats looking to simplify their finances, this helpful guide explains everything you need to know about mobile banking in Austria, including the following:
Wise
Looking for a bank account that meets your needs? Check out the multi-currency account from the financial experts at Wise (formerly TransferWise). Designed for international lifestyles, the account lets you move money without hidden fees, make and receive payments like a local, and get account details in 10 currencies. Make your finances smarter in Austria with Wise.

Mobile banking in Austria
Essentially, there are two main forms of mobile banking in Austria – standalone mobile banks and mobile banking apps from traditional banks. Although they might not offer quite as many features as traditional banks, mobile banks and mobile banking apps can still be very useful. As such, they can be a great option for expats living in Austria. They also offer the benefit of being a very eco-friendly form of banking, since everything is done online and there is no physical paperwork involved.
Despite the advantages of mobile banks and mobile banking apps, cash payments and traditional banks are still very much preferred in Austria. This is largely because Austria remains a traditional society. However, digital banking and payments are slowly gaining ground in the country. In fact, digital payments account for some €10,000 million a year and mobile payments are valued at about €2,192 million a year. Digital-only banks operating in Austria include:
Many traditional banks are also capitalizing on the growing popularity of mobile banking. This has seen them releasing increasingly sophisticated mobile apps that you can read about further down this guide.
Advantages of mobile banking over traditional banking
Although they offer many of the same account services, there is a difference between traditional banking and mobile banking. Specifically, traditional banks offer more services and different types of accounts. For example, they might be able to offer loans, overdrafts, insurance, and investments, which many mobile banks cannot.
That said, mobile banking apps can usually offer these services because they are connected to traditional banks which can offer them. Another key difference traditional banks and mobile banks is that you will not be able to go into a branch for face-to-face transactions.
Notably, in Austria, it is more difficult to open a traditional bank account as an expat. Furthermore, you have to pay more fees to have a traditional bank account, including account maintenance fees, paper account statement fees, and fees for in-person transactions; although many of these can be avoided if you primarily use your bank’s mobile banking app.
But perhaps what is more important for expats is the fact that traditional banks charge higher international transfer and foreign exchange fees, even if these are executed through an app. Additionally, mobile banking is far more sustainable because everything is done online. That said, traditional banks do offer more CSR initiatives. Despite this, both traditional and mobile banks are safe and secure, and offer similar security protocols.
Mobile banks in Austria
Features of mobile banks in Austria
Austria’s mobile banks typically offer several different types of current account. Because of this, you will be able to find one that suits your needs exactly. For example, the entry-level N26 Standard is a free personal everyday account that is suitable for everyone. Conversely, the top-tier N26 Metal is a premium account that comes with a host of extras and a metal debit card. In addition, N26 offers four levels of business bank accounts that offer similar functionality and services to the personal accounts.
Although the features vary depending on which account you have, N26 generally offers the following services through its platform:
- Full-service bank account
- 100% mobile banking for all transactions
- Contactless payments enabled by NFC technology
- Mobile payments through smartphone
- 3-8 free withdrawals per month via ATM in Eurozone
- Instant EU-wide transfers with SEPA Instant Credit Transfer
- Free worldwide payments in 38 different currencies using built-in Wise feature
- Request payment from contacts with email or phone number
- MasterCard-brand debit card that is accepted worldwide
- Contactless payments enabled by NFC technology
- No hidden fees
- Premium accounts get travel insurance that covers flights, luggage, and medical
- Some premium accounts also offer insurance for mobile phones, winter sports, and car rentals
- See your account statistics for insights on your spending
- Create subaccounts for better budgeting and saving
- Create shared accounts for joint expenses
- Access premium partner offers and experiences
- Get 24/7 support through Chatbot, in-app live chat feature, or phone

How to open a mobile bank account in Austria
In Austria, mobile banking is very accessible and there are very few restrictions when opening an account, making it very easy to do. Generally, to set up a mobile bank account, you will need to provide personal details such as your name, birthday, email, phone number, address, and tax information.
After this, you will need to confirm your identity by uploading a scan of your photo ID, such as a passport or resident card. Conveniently, the whole process can be done in a matter of minutes.
Mobile bank fees in Austria
The biggest advantage of banking online is that there are very few fees. For N26, for example, you will only need to pay a monthly account service fee. However, depending on what type of account you have, this might range from between €0 and €16.90 per month. There are no other hidden costs or transaction fees, either, which makes mobile bank accounts very easy and affordable to use. In addition, N26 doesn’t charge any foreign exchange fees on international transfers, which is very appealing to expats.
Mobile payments in Austria
As mentioned, cash is still very popular in Austria, and most everyday payments are made this way. That said, different payment options are gaining popularity, including mobile payments. In fact, the transaction value was estimated at around US$2.596 billion in 2020 and is expected to grow by 49.1% annually between 2020 and 2024. Furthermore, Statista projects that the number of users of mobile POS payments will reach 2.3 million by 2025.
All of this is underpinned by Austria’s growing mobile payments infrastructure. For example, while shopping online with debit cards and digital wallets is popular, there is a growing space for QR codes, services like Mobiamo, and contactless NFC (near-field communication) technology. In addition, many banks are enabling mobile banking in Austria by allowing customers to link their mobile apps to third-payment payment services such as Apple Pay.
Security with mobile banking in Austria
Like all banks, mobile banks take security very seriously. As such, if you choose to use a mobile bank while you are living in Austria, you can also rest assured that your finances are safe. In fact, most mobile banks use the same kind of security protocols and technologies that traditional banks use.
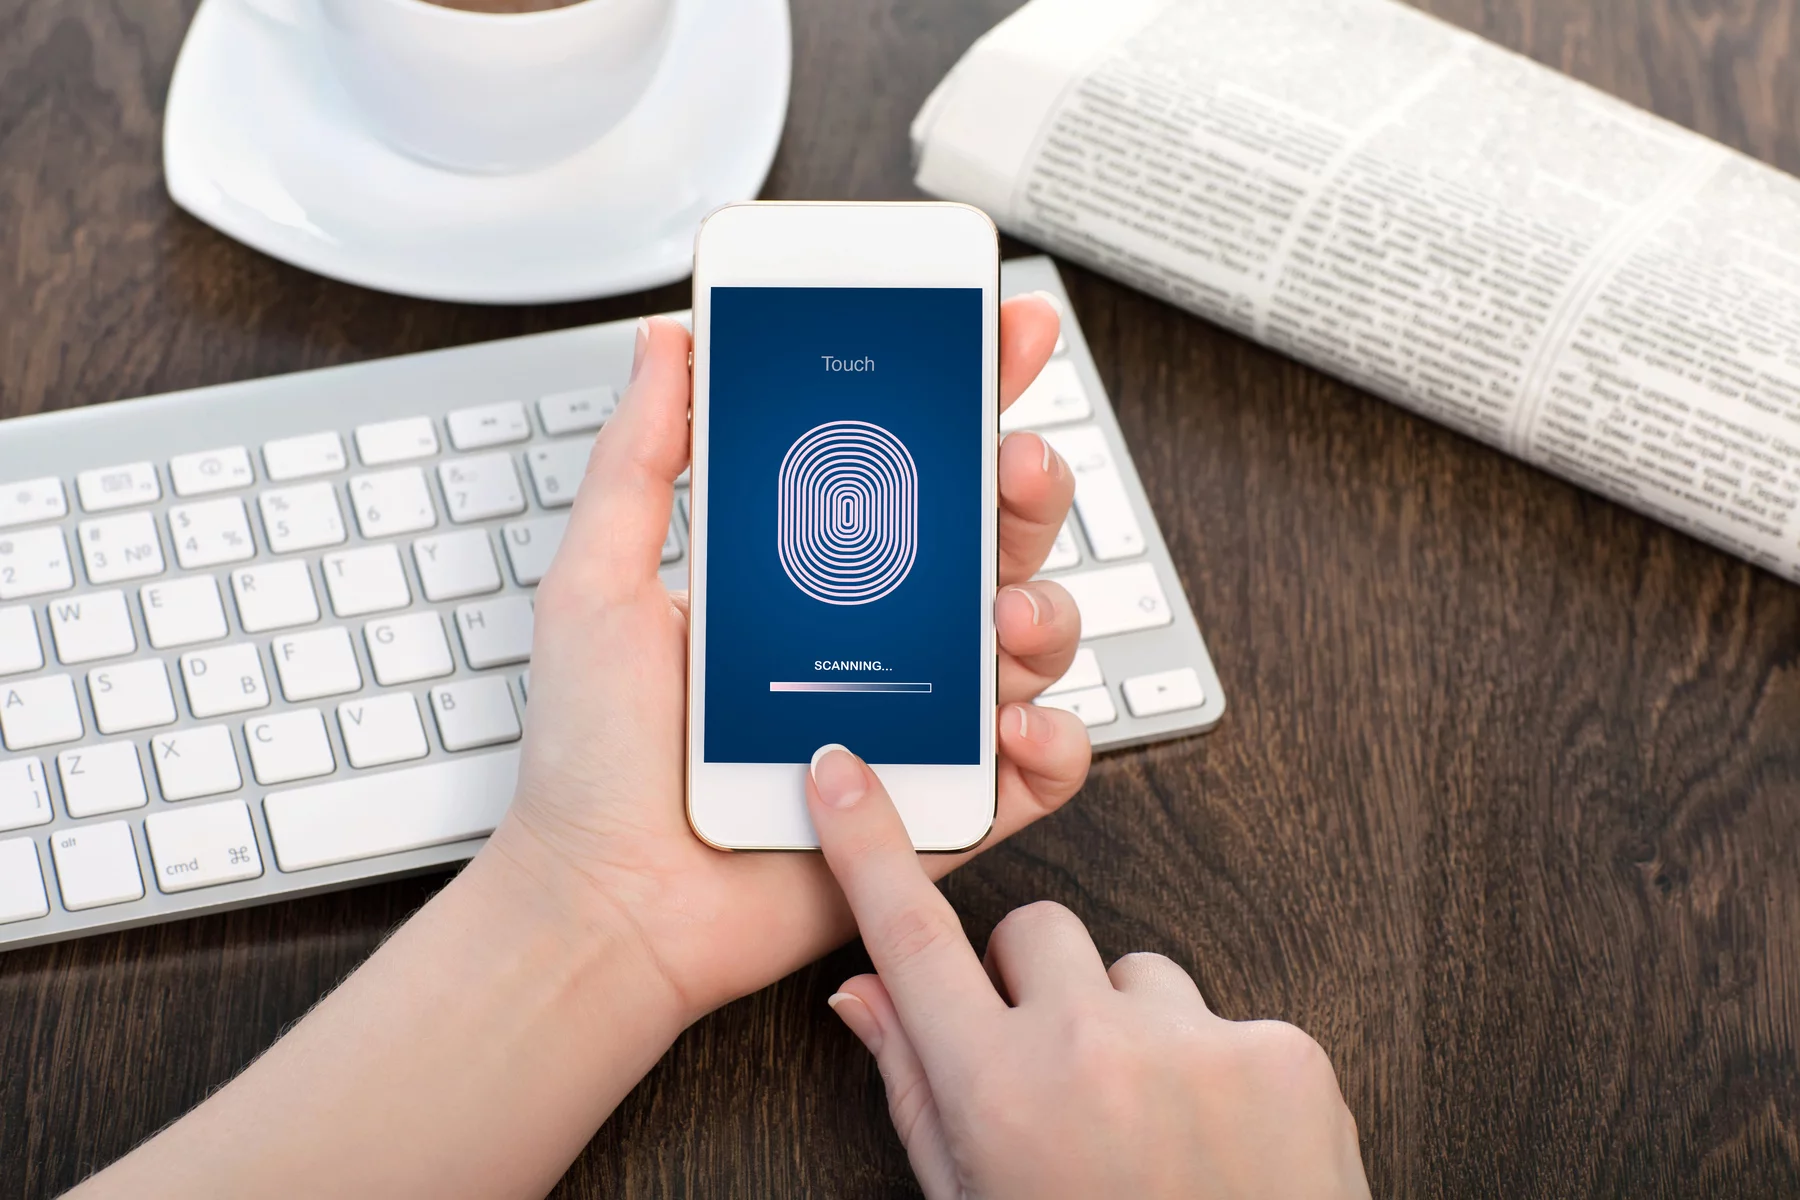
For example, N26 has a full European banking license. As such, it offers a German IBAN with deposit protection up to €100,000, in line with EU guidelines. In addition, it secures payments with advanced 3D Secure technology and fingerprint identification or two-factor authentication. Many mobile banking apps – including Erste Bank’s George and Bank Austria’s MobileBanking – use similar security features, as well as Face and Touch ID, and QR code support for transfers.

Furthermore, you will immediately receive notifications on your phone for all transactions, including payments, withdrawals, direct debits, and transfers, so you can immediately identify suspicious activity. If you lose your debit card, you can simply block the card in the app and reorder it.
Mobile banking apps in Austria
Banks with mobile banking apps in Austria
Fortunately, most traditional Austrian banks offer branded apps to facilitate mobile banking, making it easier for expats to manage their finances in the long run. For example, customers of Erste Bank and Sparkasse can handle their accounts through the banks’ app, George.
Mobile banking app features in Austria
Generally speaking, most banking apps in Austria offer customers the same features, which are as follows:
- See a full overview of your accounts and money
- Easy transfers, including SEPA
- Intelligent address books
- Scanning for IBAN and money orders
- Secure, contactless payments through Apple Pay
- Manage all transfer and payment limits
- Appointment booking for face-to-face meetings
- Check linked investments or insurance policies
- Execute trades
- Issue standing orders and autopays
How to use a mobile banking app in Austria
Luckily for expats, using mobile banking apps is fairly straightforward. If you already have an account at a bank in Austria, for instance, you can simply download the bank’s mobile banking app and use your existing account information to create an app profile and access all its features. If you don’t have an existing account with an Austrian bank, however, you will need to open an account with the bank before you can download and start using the bank’s app.
To open an Austrian bank account, you will need to have the following documents at hand:
- your proof of identity (for example, your passport)
- proof of residency (such as a Residency Registration Form or utility bills)
- your proof of employment (such as an official job contract)

Notably, if you are an EU/EEA national, you will find that opening a bank account in Austria is much simpler than third-country nationals. Certain banks, such as Erste, allow non-residents to open accounts. Furthermore, foreigners are able to manage funds in all currencies, get the latest exchange rates, and make credit transfers in foreign currencies. However, you will need to go to the bank in person to apply for this.
Mobile banking app fees in Austria
If you use your bank’s mobile app, you can expect to pay the standard banking fees that your account may incur. For example, Bank Austria charges a monthly service fee for all its accounts, ranging from €2.03 to €8.16 per month. In addition, customers may have to pay fees for certain services and transactions such as requesting an account statement at an ATM (€3.06). That said, these are not usually directly related to the use of the mobile app.
Useful resources
- appfigures – the top finance apps in Austria
- Consumer Financial Protection Bureau (CFPB) – article on Online and mobile banking tips for beginners
- Kasasa – article on Mobile Banking Security Tips: Is Your Information Safe?
- N26 – article on Tips for secure mobile banking

Did you find this guide helpful?